France’s Wine Harvest Just Hit a 70-Year Low — Here’s Why

France is heading for its smallest wine harvest in 70 years. The France wine production crisis now unfolding is reshaping an industry. That industry has already shed businesses at triple the normal rate over the past six years.

The country’s agriculture ministry expects winemakers to produce under 34 million hectolitres in 2026. That figure sits 6% below 2025’s already-weak harvest. It is 17% under the recent five-year average, per government estimates reported this week.
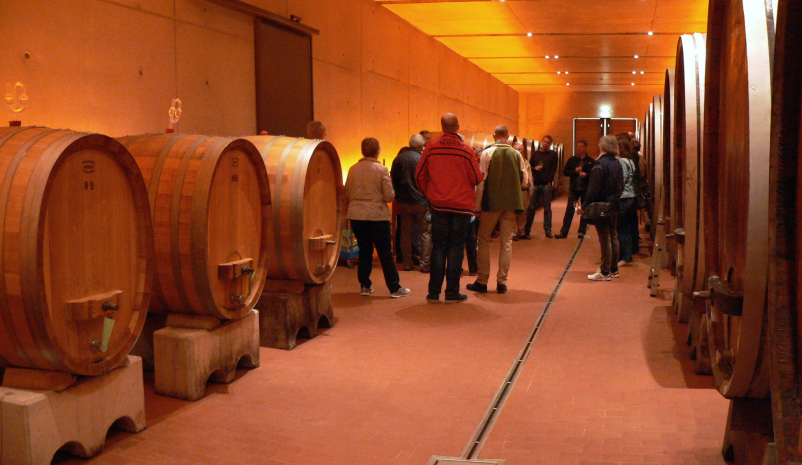
Wine barrels in a French cellar amid the France wine production crisis

How Bad the France Wine Production Crisis Has Gotten

This is the third straight year of reduced French wine output. That run has compounded financial pressure on growers already working thin margins. Industry data shows wine-sector business failures tripled between 2019 and 2025. Officials warn 2026 risks matching that pace.

The decline arrives at an awkward commercial moment too. A smaller harvest leaves French producers with less volume for export. That coincides with the government’s push to shrink the sector’s footprint. It runs its shrinking effort through a vine-removal program. Growers’ associations say the combination makes the coming year unusually hard to plan around.

Heat and Drought Behind the Shrinking Harvest

A record-breaking summer of intense heat and severe drought decimated yields. The damage hit France’s key growing regions hardest. It was not evenly spread, though. Areas with more temperate climates took some of the hardest hits this time. Those areas historically buffered French wine against extreme weather.

Champagne and the Loire Valley Are Taking the Hardest Hit

The Loire Valley and Champagne emerged as the regions suffering most. That is per the agriculture ministry’s own assessment. Both depend on cooler growing conditions that this year’s heat undermined. Growers in both regions face some of the steepest year-on-year declines in the country.

That pattern breaks from expectations a decade ago. Back then, warmer southern regions seemed most exposed to climate stress. Instead, vineyards built around narrower temperature windows are proving more fragile. That shift is forcing growers across multiple regions to rethink old assumptions about which sites are climate-resilient.

Paris Steps In With Emergency Money

The French government announced an emergency aid plan worth more than €1 billion, or $1.15 billion. It targets farmers and winegrowers hit by the heatwaves. Separately, a vine-removal program pays growers €4,000 per hectare to permanently uproot vines. Around 4% of France’s vineyards are being pulled up nationwide this year. That effort aims to right-size an oversupplied, shrinking market.

The Wider Squeeze on European Agriculture

France is not alone. Growers across southern and western Europe have reported similar heat and drought stress this year. But France’s scale makes its decline especially visible. It is the world’s second-largest wine producer by volume. Wine merchants are already bracing for tighter supply and higher prices on French labels heading into 2027. Champagne stands out, since its limited growing area leaves little room to offset a bad harvest.

Some producers are lobbying Brussels for EU-wide climate adaptation funding. They would rather not rely solely on national aid packages. They argue a problem this widespread needs a response bigger than any single government can offer.

Export Markets Are Watching Closely

French wine exporters sell heavily into the United States, the United Kingdom and China. Buyers in all three markets have started asking suppliers about 2026 allocation early. A tighter harvest usually means exporters ship less overall. It also means they prioritize their higher-margin labels first. Smaller négociants without long-standing contracts could find themselves squeezed out of some markets entirely next year.

Trade groups are urging producers to lock in export contracts now, before final harvest numbers are confirmed. Doing so, they say, would avoid a scramble for allocation once buyers see just how tight 2026 supply really is.

What This Means for the Next Vintage

Experts tracking the sector note that Spain has adapted more successfully to the same climate pressures. That comparison is fueling debate inside France. Growers are asking whether they need to shift varietals or growing techniques, rather than simply wait for better weather. With a third straight down year now confirmed, industry watchers expect the vine-removal program to expand, not wind down, in 2027.

For now, French officials are framing the crisis as a turning point rather than a one-off bad year. How the sector adapts over the next two harvests will likely shape French wine policy for the rest of the decade.

Consumers may not feel the squeeze right away. Larger producers typically hold reserve stock that can cushion a single bad harvest. A third straight weak year leaves less of that buffer to draw on, though, which is part of why growers and officials alike are treating 2026 as more than an isolated setback.

Questions About France’s Wine Crisis, Answered

How bad is the France wine production crisis this year?

France’s agriculture ministry expects under 34 million hectolitres in 2026, a 6% drop from 2025 and 17% below the recent five-year average.

What is causing the shortfall?

A record-breaking summer of intense heat and severe drought hit yields hardest in the Loire Valley and Champagne.

Is this the first bad year in a row?

No. 2026 marks the third consecutive year of reduced French wine output.

What is the government doing about it?

Paris announced an emergency aid plan worth more than €1 billion ($1.15 billion) for affected farmers and winegrowers.

Are vineyards being removed?

Yes. Around 4% of French vines will be pulled up nationwide under a government program paying growers €4,000 per hectare for permanent uprooting.

Sources

More business coverage on Tamara News: Africa’s biggest-ever IPO drew big money in its first hour and gold’s slide to a six-week low ahead of the rate hike.
Africa’s Biggest-Ever IPO Just Opened, and It Drew Big Money in Its First Hour

Africa’s largest-ever share sale opened on September 14, and demand arrived almost immediately. The Dangote refinery IPO is offering 4.1 billion shares in Dangote Petroleum Refinery and Petrochemicals FZE at 525 naira, roughly $0.40, each. Within the first hour of trading, subscription value reportedly reached around 1.5 trillion naira.

The offering runs from September 14 to October 13 on Nigeria’s main stock exchange. If fully subscribed, it would raise 2.15 trillion naira, about $1.6 billion, and that figure could climb toward $2.1 billion if the offer is oversubscribed and Dangote exercises a greenshoe option to issue additional shares.

The short version: The IPO opened September 14. It closes October 13. 4.1 billion shares are on offer. The target raise is $1.6 billion. Demand hit ₦1.5 trillion in hour one. Proceeds fund a capacity expansion.

What the Dangote Refinery IPO Is Actually Selling

The shares being offered sit in the entity that operates Africa’s largest oil refinery, built by billionaire Aliko Dangote. Nigeria’s Securities and Exchange Commission approved the sale on September 4, clearing the way for what is being described locally as a “people’s IPO” aimed at broadening domestic share ownership in one of the country’s most significant industrial assets.

The regulator’s approval cleared the way for trading to open ten days later. That is a tight turnaround for a deal this size. It signals the government wants this listing to succeed. A stumble here would sting Nigeria’s broader market ambitions.

Why This Is Nigeria’s Biggest IPO

At a targeted raise of $1.6 billion, this is the largest initial public offering ever attempted on the Nigerian Exchange. The scale reflects both the size of the refinery itself and the ambition behind it. The facility already ranks among the largest single-train refineries in the world, and its influence on Nigeria’s fuel imports and pricing has been significant since it began full operations.

What the IPO Money Will Fund

Proceeds are earmarked for a planned expansion that would double the refinery’s processing capacity to 1.4 million barrels per day. That expansion would extend Dangote’s reach into export markets and further reduce Nigeria’s reliance on imported refined fuel, a dependency that has weighed on the country’s currency and trade balance for years. Nigeria has spent billions importing fuel for decades. That spending drained foreign reserves every year. A larger refinery flips that equation, at least in part, by keeping more of that money at home.

The refinery already ranks among the largest single-train facilities anywhere in the world, and doubling its capacity would push it further up that list. Industry analysts say the expansion could reshape fuel trade flows across West Africa, where several neighboring countries currently rely on imported refined products rather than domestic refining capacity of their own.

Why This IPO Carries Weight Beyond Nigeria

Africa’s capital markets have historically struggled to attract IPOs of this scale, with many large African companies choosing to list on exchanges in London or New York instead. A successful, oversubscribed listing on the Nigerian Exchange would be read as a signal that African markets can absorb billion-dollar offerings without routing them abroad. That signal matters for other large private companies across the continent weighing where to eventually go public. A strong close in October, when the offer window ends, would be the clearest test yet of whether that shift is actually underway.

What Investors Are Watching

The strong first-hour demand suggests appetite among both domestic and international investors, though the six-week subscription window means the final outcome will not be clear until mid-October. Analysts are watching whether retail investor participation, a stated goal of the “people’s IPO” framing, materializes at scale or whether institutional investors end up dominating the book. Retail-heavy ownership tends to keep a stock more stable over time. Institution-heavy ownership can swing faster on sentiment. Either outcome will shape how the shares trade once they list.

The greenshoe option is another detail worth tracking. If demand significantly outstrips the base offering, Dangote can issue additional shares to capture that extra appetite, pushing the total raised closer to $2.1 billion rather than the base $1.6 billion target. Whether that extra demand materializes should become clear well before the window closes in mid-October.

The numbers at a glance: Offer opened: September 14. Offer closes: October 13. Shares on offer: 4.1 billion. Share price: 525 naira. Base target: $1.6 billion. Upside with greenshoe: about $2.1 billion.

Investor Questions About the Dangote IPO

How many shares are being offered?
4.1 billion shares at 525 naira (about $0.40) each.

How much could the IPO raise?
Up to 2.15 trillion naira (about $1.6 billion), or roughly $2.1 billion with the greenshoe option.

When does the offer close?
October 13, 2026.

What will the money be used for?
Doubling the refinery’s processing capacity to 1.4 million barrels per day.

Who approved the IPO?
Nigeria’s Securities and Exchange Commission, which cleared the sale on September 4.

Other Stories Worth Your Time

Sources

  • Bloomberg — Dangote Seeks to Raise $1.6 Billion in Nigeria’s Biggest IPO. bloomberg.com
  • CNBC Africa — Billionaire Dangote Launches Oil Refinery ‘People’s IPO’, Africa’s Biggest. cnbcafrica.com
  • UrbanGeekz — Dangote Refinery Launches Africa’s Largest-Ever IPO. urbangeekz.com

This AI Firm Grew Revenue 1,252% and Still Lost $1 Billion

The Nscale IPO filing landed publicly on 18 September 2026, and it is one of the
starkest illustrations yet of how much money the AI build-out is consuming. The London-based data centre
operator, backed by Nvidia and partnered with Microsoft, filed with the US Securities and Exchange
Commission to list in New York. It is seeking as much as 3 billion dollars, at a valuation reported at
around 30 billion.

The numbers inside the Nscale IPO filing

For the six months to 30 June 2026, Nscale reported revenue of 140.6 million dollars and a net loss of
1.02 billion dollars. A year earlier it reported revenue of 10.4 million dollars and a net loss of 368.9
million dollars. Revenue therefore grew about 1,252 percent. Losses grew too, and faster in absolute
terms.

That shape is normal for infrastructure at this stage. Data centres cost money years before they earn
it. The question a buyer has to answer is whether the contracted demand is real enough to carry the
spending.

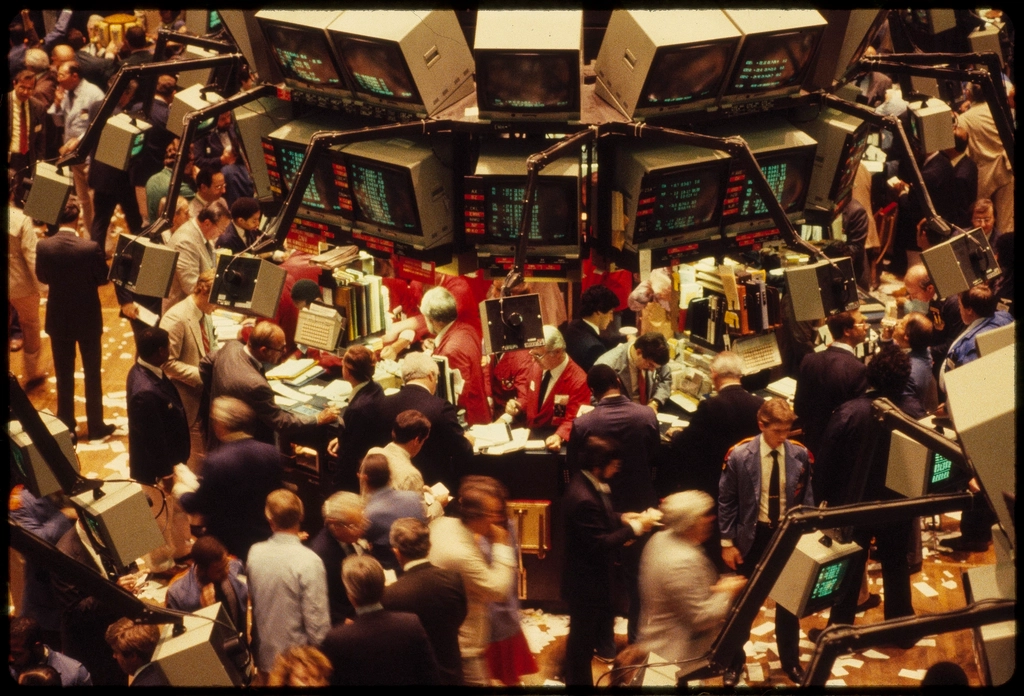
New York Stock Exchange floor, the venue for the Nscale IPO filing
Nscale is filing to list in New York rather than London.

What the filing claims about contracted demand

Nscale says it has grown to more than 103 billion dollars in total contracted value, up from 100 million
dollars in two and a half years. That figure comes from the company’s own filing and describes contracts
over their full life, not revenue already earned. Read it as a pipeline number.

One named commitment gives it weight. Anthropic agreed last month to spend 45 billion dollars renting AI
cloud capacity from Nscale’s West Virginia data centre campus. A single customer of that size cuts both
ways: it validates the model and it concentrates the risk.

Why Nvidia keeps showing up in the Nscale IPO filing

Nvidia is an investor, a supplier and now a buyer of Nscale paper. The company agreed this week to sell
3.1 billion dollars of convertible bonds, including 1 billion dollars to Nvidia, according to the filing.
Nvidia is funding a customer that buys Nvidia chips. That circularity is not hidden, but it is worth
naming.

It is the same pattern visible elsewhere in the sector. We looked at the financing loops around the
largest AI labs in our coverage of
the valuation talks reshaping OpenAI
and
the loan SoftBank arranged against its OpenAI stake.
Nvidia has also been buying its way up the stack, as in
its acquisition of Hugging Face.

The risks a prospective investor should weigh

Three stand out. Customer concentration comes first. A pipeline dominated by a handful of AI labs
depends on those labs continuing to raise money. Capital intensity comes second. Nscale needs continuous
financing to build, and it already leans on convertible debt. Supply comes third, because memory and grid
capacity are both tight in 2026.

Power deserves its own line. AI campuses compete with households and industry for grid connections, and
connection queues in the United States and Europe now run for years. A contract only earns revenue once
the site draws power.

None of that disqualifies the deal. All of it belongs in the price.

What to watch before Nscale prices the deal

A public filing opens the window. It does not set the terms. Watch for the pricing range, the share
count and the lock-up terms when they appear in an amended filing. Watch whether Nscale restates or breaks
down the contracted-value figure. And watch the comparable names: if AI infrastructure valuations move in
the next few weeks, the 30 billion dollar target moves with them.

One more signal is worth tracking. If Nvidia’s stake grows again between now and pricing, the
supplier-financier overlap tightens rather than loosens.

You can read the filing itself once it appears in the
SEC’s EDGAR database,
which is the primary record rather than anyone’s summary of it.

Questions investors are asking about the Nscale IPO filing

What is Nscale?

Nscale is a London-based operator of artificial intelligence data centres and cloud capacity. Nvidia is an investor and Microsoft is a partner.

How much is Nscale trying to raise?

The company is seeking up to 3 billion dollars in the offering and is targeting a valuation of around 30 billion dollars, according to reporting on its filing.

Is Nscale profitable?

No. It reported a net loss of 1.02 billion dollars on revenue of 140.6 million dollars for the six months to 30 June 2026.

Why did revenue jump so sharply?

Revenue rose from 10.4 million dollars to 140.6 million dollars year on year, a rise of about 1,252 percent, as large AI customers contracted capacity.

Who are its biggest customers?

The filing points to large AI buyers. Anthropic agreed last month to spend 45 billion dollars renting cloud computing power from Nscale’s West Virginia campus.

When will the shares start trading?

No pricing date has been set publicly. A public filing starts a roadshow window; the terms and timing are confirmed later.

Sources

Featured image: "Quincy Data Centre" by cellanr, CC BY-SA 2.0.

airBaltic Just Filed for Bankruptcy. Its Planes Are Still Taking Off on Schedule.

airBaltic, the Latvian flag carrier, filed for Chapter 11 bankruptcy protection in a US court on September 14. The move sounds alarming, but the airBaltic bankruptcy financing package attached to the filing means passengers are unlikely to notice any difference at the gate. Every scheduled flight is still operating, and the airline says it expects that to continue through the restructuring.

The filing was made with the US Bankruptcy Court for the Southern District of New York. airBaltic described its situation as acute financial stress driven by a mix of financial and geopolitical pressures, from fuel costs to the security environment around the Baltic region.

The short version: airBaltic filed for Chapter 11 on September 14. Flights are still operating on schedule. Lenders committed €350 million in financing. The court approved an initial €140 million. The full process should wrap by June 2027. Tickets and loyalty points stay valid throughout.

What airBaltic’s Chapter 11 Filing Actually Means

Chapter 11 is a US legal process that lets a company keep operating while it reorganizes its debts under court supervision. It does not mean the airline is shutting down. airBaltic said flights will run as scheduled throughout the process, which it expects to complete by June 2027.

For travelers, existing tickets and loyalty points remain valid. Airlines that use Chapter 11 protection, rather than liquidation, are choosing a path meant to keep the business flying while it renegotiates what it owes.

airBaltic Bankruptcy Financing: How the €350 Million Works

airBaltic secured a commitment for €350 million in debtor-in-possession financing from a group of lenders that includes Strategic Value Partners, Barclays, Hayfin Capital Management, Morgan Stanley and Oaktree Capital Management. The funding carries a rate of roughly 12%, reflecting the risk lenders take on during a restructuring.

On September 16, the bankruptcy court granted interim approval for airBaltic to draw an initial €140 million of that facility. The remaining amount is subject to further court approval as the case proceeds.

Why the Baltic Carrier Ran Out of Room

airBaltic operates from Riga, close to the Baltic Sea and within range of the war in Ukraine. Airlines in the region have absorbed years of higher insurance costs, longer rerouted flight paths and volatile fuel prices. Combined with the broader financial strain many mid-sized European carriers face, the airline said it reached a point where restructuring was the more sustainable path forward.

What Passengers Should Expect

Nothing changes immediately for people holding tickets. airBaltic has stated publicly that its flight schedule continues unaffected during the court-supervised process. Passengers with upcoming bookings do not need to rebook or seek refunds because of the filing itself.

How This Compares to Other Airline Bankruptcies

Chapter 11 has become a familiar tool for airlines under financial strain, used in the past by carriers on both sides of the Atlantic to shed debt while continuing to fly. What sets the airBaltic bankruptcy financing package apart is its size relative to the airline itself. A €350 million facility is a substantial sum for a regional carrier of airBaltic’s scale, reflecting both the severity of its cash crunch and the confidence lenders still have in its long-term business.

Rating agency KBRA noted that the financing terms, while expensive at roughly 12%, give airBaltic room to keep operating without disruption to passengers, crews or its fleet of Airbus A220 aircraft, a newer, fuel-efficient jet the airline has leaned on heavily in recent years.

What Happens Next for airBaltic

The case will move through the US court over the coming months, with airBaltic expected to present a formal reorganization plan to creditors. The airline has set an internal target of finishing the process by June 2027. Credit analysts are watching how the airline balances debt reduction against keeping its route network intact, particularly its connections between the Baltic states and Western Europe that many smaller communities depend on for air access.

Latvia’s government, which holds a stake in airBaltic, has signaled continued support for the airline through the restructuring, though it has not detailed what additional state involvement, if any, might follow.

The numbers at a glance: Filing date: September 14. Financing commitment: €350 million. Initial court-approved draw: €140 million. Interest rate: roughly 12%. Target completion: June 2027. Flights affected so far: none.

Common Questions About the airBaltic Filing

Did airBaltic stop flying?
No. The airline says all scheduled flights continue to operate during the Chapter 11 process.

What is debtor-in-possession financing?
It is a loan that lets a company keep paying its bills and running operations while it works through bankruptcy court.

How much financing did airBaltic secure?
A commitment for €350 million, with an initial €140 million approved for immediate use.

When does airBaltic expect the process to end?
The airline has targeted completion by June 2027.

Are existing tickets still valid?
Yes. airBaltic has not asked passengers to take any action because of the filing.

Keep Reading

Sources

  • RTE — AirBaltic Voluntarily Files for US Bankruptcy Protection. rte.ie
  • Aerotime — Boost for airBaltic as US Bankruptcy Court Approves Access to Financing. aerotime.aero
  • Airways Magazine — airBaltic Files for Chapter 11 With €350m Financing Commitment. airwaysmag.com

Broadcom Smashed Earnings — So Why Did Investors Sell the Stock?

Broadcom shares fell after the company issued fourth-quarter guidance that trailed Wall Street’s target. The Broadcom revenue forecast miss overshadowed a blowout third quarter built on soaring AI chip sales. Broadcom told investors to expect roughly $34.8 billion in fiscal fourth-quarter revenue. Analysts polled by LSEG had expected about $35.03 billion, according to Reuters. The gap is small in percentage terms. But it landed on a stock priced for perfection, and traders sold first and asked questions later.

The Broadcom revenue forecast miss, by the numbers

Broadcom’s own numbers tell two different stories. The third quarter, reported on September 2, was excellent. Revenue hit $29.6 billion, up 86% from a year earlier, according to the company’s investor relations release. Non-GAAP operating income reached $20.1 billion, a 92% jump. Free cash flow came in at $13.7 billion, or 46% of revenue.

Broadcom revenue forecast miss: inside a semiconductor fabrication facility

The trouble sits in the outlook. Broadcom guided fourth-quarter revenue to about $34.8 billion. That still marks 93% growth from a year earlier. Yet it fell short of the $35.03 billion consensus tracked by LSEG. Bloomberg’s own survey put the average estimate near $35.1 billion, with some analysts modeling above $36 billion. Broadcom also guided non-GAAP operating margin to about 66% of revenue for the quarter, flat against the year-ago period. Wall Street had penciled in further margin expansion, not a plateau.

What Hock Tan and Amie Thuener Told Investors

Broadcom CEO Hock Tan pointed to a specific growth engine. “Demand for our custom AI accelerators and networking continues to be very strong,” Tan said in the earnings release. He noted that AI semiconductor revenue reached $16.7 billion in the third quarter, up 221% year-over-year and 54% from the prior quarter. Tan told investors that momentum would continue. He guided AI semiconductor revenue to climb to $21.7 billion in the fourth quarter, a 236% annual increase.

CFO Amie Thuener echoed that confidence while acknowledging the flat margin outlook. “We delivered non-GAAP operating income growth of 92% year-over-year, as consolidated revenue grew 86% year-over-year to $29.6 billion,” Thuener said. She added that fourth-quarter revenue growth is forecast at 93% year-over-year, with the non-GAAP operating margin held at 66%, flat from a year ago. Investors read that as a signal. Heavy investment, not weakening demand, is compressing near-term profitability.

AI Chip Demand Is Soaring — So Why the Forecast Gap?

Broadcom’s custom AI chip business, often called XPUs, has become central to its growth story. The company designs application-specific processors for hyperscale customers, including Alphabet’s Google. Google’s tensor processing units, built with Broadcom, sit at the center of that partnership. Broadcom has also helped arrange financing so Anthropic can buy the computing power its custom chips help produce. That build-out sits inside a wider debate over chip export bills touching Anthropic and the industry group ITI. Export strength elsewhere reinforces the point. South Korea’s chip exports hit a record in the same stretch, a sign that global AI infrastructure spending has not slowed.

Competition is the other half of the story. Rival Nvidia delivered a strong forecast of its own the week before Broadcom reported. Bloomberg Intelligence analysts said Nvidia had set a high sales bar for the rest of the sector. Marvell Technology and MediaTek are both racing to win custom chip work, and both count Nvidia as a backer. Marvell announced a deal last month to help build custom semiconductors for Google, a customer Broadcom has long served. That competitive pressure, more than any drop-off in AI demand, appears to explain the cautious guidance.

How Wall Street Reacted to the Forecast Miss

Broadcom shares dropped about 4% in after-hours trading once the numbers landed, according to Bloomberg. The stock had climbed roughly 6% for the year heading into the report, leaving little room for disappointment. Some analysts pushed back on the sell-off. Bernstein’s Stacy Rasgon said the underlying quarter was strong. He called the results very, very good and noted that semiconductor revenue actually landed slightly above expectations. Other analysts framed the move as a reset in expectations after a run of AI-driven gains, rather than a sign of fading demand.

What Comes Next for Broadcom’s AI Chip Business

Broadcom’s own guidance points to continued expansion, not contraction. Management has said it expects AI-related revenue to keep growing sharply into fiscal 2027 and 2028, based on commitments already on the books. Broadcom is not alone in wiring multi-year AI compute commitments into today’s numbers. OpenAI has been in its own funding talks tied to a rising valuation, and its backers are locking in the same kind of long-term computing bets Broadcom is chasing with Anthropic. The financing arrangements with Apollo Global Management and Blackstone still need to close and fund actual chip purchases, a process that will take years to play out. Investors will also watch whether new custom chip customers emerge beyond Google, and whether Broadcom can defend its lead against Marvell and MediaTek. The next real test comes when Broadcom reports fourth-quarter results in December. The market will then see whether $34.8 billion in revenue landed, or beat it.

Frequently Asked Questions

What is the Broadcom revenue forecast miss?

The Broadcom revenue forecast miss refers to the company’s fourth-quarter guidance of about $34.8 billion, below the $35.03 billion analysts expected, according to LSEG data cited by Reuters.

Why did Broadcom stock fall after strong earnings?

Shares fell because the fourth-quarter outlook missed consensus estimates, even though third-quarter revenue grew 86% and beat expectations. Investors focused on the forward guidance rather than the results already reported.

How much did Broadcom’s AI chip revenue grow?

Broadcom’s AI semiconductor revenue reached $16.7 billion in the third quarter, up 221% from a year earlier. The company guided AI semiconductor revenue to $21.7 billion for the fourth quarter.

What operating margin did Broadcom guide for the fourth quarter?

Broadcom guided non-GAAP operating margin to approximately 66% of revenue for the fourth quarter, flat compared with the year-ago period.

Is competition affecting Broadcom’s custom chip business?

Yes. Marvell Technology and MediaTek are both pursuing custom AI chip deals, and Nvidia’s own strong forecast the week before Broadcom’s report raised expectations across the sector.

Does the forecast miss mean AI chip demand is slowing?

Not according to Broadcom’s own numbers. Guidance still calls for 93% year-over-year revenue growth in the fourth quarter. Analysts including Bernstein’s Stacy Rasgon described the underlying business as strong.

Sources