Paramount Just Cleared Its Biggest Hurdle to Owning Warner Bros

The Paramount Warner Bros. Discovery merger cleared its most significant remaining obstacle on September 21, when Paramount Skydance reached a settlement with 12 state attorneys general and the Writers Guild of America, resolving the legal challenges that had threatened to delay or unwind the $111 billion acquisition. The deal is now expected to close by October 1, 2026.

What the settlement actually requires

The agreement isn’t just a legal formality — it locks Paramount into specific production commitments. Under the terms reported by CNBC and detailed further by Axios, the combined company must produce 30 films a year for its first two years post-merger, including 20 wide theatrical releases, rising to 32 films annually in years three through five. Missing those targets triggers a $30 million penalty per film. Paramount also committed to $1.5 billion in US film production investment over five years, plus additional funding earmarked for independent films and workforce training programs — provisions clearly aimed at addressing union and state concerns about job losses from combining two major studios.

Why states and the union pushed back in the first place

The settlement, described as resolving concerns “without endorsing the merger outright,” reflects the core tension regulators and unions raised from the start: combining Paramount and Warner Bros. Discovery consolidates two of Hollywood’s largest production and distribution operations under one roof, raising the risk of reduced production volume, fewer competing buyers for scripts and talent, and job cuts as overlapping units get merged. The production quotas and penalty structure are a direct answer to that risk, converting a settlement into an enforceable floor on how much work the merged studio has to keep generating.

The money behind the deal

Financing the $111 billion transaction is requiring Paramount to take on substantial additional debt. The company is raising billions more in financing specifically to fund the Warner Bros. side of the deal, on top of the debt already layered into the transaction’s original structure — a detail that valuation-focused analysts have flagged as a factor to watch once the combined company starts reporting results.

How this fits the broader wave of media consolidation

The Paramount-Warner Bros. Discovery tie-up is the largest in a run of media and entertainment deals this year, part of a broader trend of legacy studios and streaming platforms combining scale to compete against tech-backed entrants for both subscribers and advertising dollars. Analysts covering the sector have noted that the production-quota structure baked into this settlement, guaranteed film output backed by financial penalties, could become a template regulators reach for in future entertainment mergers, since it addresses the jobs argument against consolidation without blocking the deal outright.

Industry observers will also be watching how quickly the combined company integrates back-office functions, streaming platforms and distribution deals, since past megamergers in media have often taken longer than announced to deliver the cost savings and content synergies executives promised investors when the deal was first proposed.

Regulators in other jurisdictions where the combined company operates are also expected to complete their own reviews before the deal is considered fully closed everywhere, though none has signaled the kind of opposition that produced this settlement in the United States.

The remaining steps to closing

With the state and union settlement in hand, the deal’s remaining path to closing is largely administrative rather than legal. Barring a late complication, Paramount and Warner Bros. Discovery are on track to combine by October 1, 2026, after which the real test begins: whether the newly merged studio can hit its mandated 30-films-a-year pace while integrating two large content libraries, streaming platforms and production pipelines without the delays that have slowed other recent media mergers.

Questions about the deal

How much is the Paramount Warner Bros. Discovery merger worth?

The acquisition is valued at $111 billion.

What did Paramount agree to in the settlement?

Paramount settled with 12 state attorneys general and the Writers Guild of America, committing to produce 30 films annually for two years (rising to 32 in years three through five), invest $1.5 billion in US film production over five years, and pay a $30 million penalty per film if it misses production targets.

When is the Warner Bros. Discovery deal expected to close?

The deal is targeted to close by October 1, 2026.

Why did states and the Writers Guild oppose the merger?

They raised concerns that combining two major studios would reduce production volume, cut competing buyers for scripts and talent, and eliminate jobs through overlapping-unit consolidation.

How is Paramount financing the acquisition?

Paramount is raising billions of dollars in additional debt specifically to fund the Warner Bros. Discovery side of the transaction.

For more on recent megadeals reshaping their industries, see our coverage of Nvidia’s $12.9 billion Hugging Face acquisition and the $1.65 billion deal reshaping cancer treatment’s supply chain.
Paramount Just Cleared Its Biggest Hurdle to Owning Warner Bros

The Paramount Warner Bros. Discovery merger cleared its most significant remaining obstacle on September 21, when Paramount Skydance reached a settlement with 12 state attorneys general and the Writers Guild of America, resolving the legal challenges that had threatened to delay or unwind the $111 billion acquisition. The deal is now expected to close by October 1, 2026.

What the settlement actually requires

The agreement isn’t just a legal formality — it locks Paramount into specific production commitments. Under the terms reported by CNBC and detailed further by Axios, the combined company must produce 30 films a year for its first two years post-merger, including 20 wide theatrical releases, rising to 32 films annually in years three through five. Missing those targets triggers a $30 million penalty per film. Paramount also committed to $1.5 billion in US film production investment over five years, plus additional funding earmarked for independent films and workforce training programs — provisions clearly aimed at addressing union and state concerns about job losses from combining two major studios.

Why states and the union pushed back in the first place

The settlement, described as resolving concerns “without endorsing the merger outright,” reflects the core tension regulators and unions raised from the start: combining Paramount and Warner Bros. Discovery consolidates two of Hollywood’s largest production and distribution operations under one roof, raising the risk of reduced production volume, fewer competing buyers for scripts and talent, and job cuts as overlapping units get merged. The production quotas and penalty structure are a direct answer to that risk, converting a settlement into an enforceable floor on how much work the merged studio has to keep generating.

The money behind the deal

Financing the $111 billion transaction is requiring Paramount to take on substantial additional debt. The company is raising billions more in financing specifically to fund the Warner Bros. side of the deal, on top of the debt already layered into the transaction’s original structure — a detail that valuation-focused analysts have flagged as a factor to watch once the combined company starts reporting results.

How this fits the broader wave of media consolidation

The Paramount-Warner Bros. Discovery tie-up is the largest in a run of media and entertainment deals this year, part of a broader trend of legacy studios and streaming platforms combining scale to compete against tech-backed entrants for both subscribers and advertising dollars. Analysts covering the sector have noted that the production-quota structure baked into this settlement, guaranteed film output backed by financial penalties, could become a template regulators reach for in future entertainment mergers, since it addresses the jobs argument against consolidation without blocking the deal outright.

Industry observers will also be watching how quickly the combined company integrates back-office functions, streaming platforms and distribution deals, since past megamergers in media have often taken longer than announced to deliver the cost savings and content synergies executives promised investors when the deal was first proposed.

Regulators in other jurisdictions where the combined company operates are also expected to complete their own reviews before the deal is considered fully closed everywhere, though none has signaled the kind of opposition that produced this settlement in the United States.

The remaining steps to closing

With the state and union settlement in hand, the deal’s remaining path to closing is largely administrative rather than legal. Barring a late complication, Paramount and Warner Bros. Discovery are on track to combine by October 1, 2026, after which the real test begins: whether the newly merged studio can hit its mandated 30-films-a-year pace while integrating two large content libraries, streaming platforms and production pipelines without the delays that have slowed other recent media mergers.

Questions about the deal

How much is the Paramount Warner Bros. Discovery merger worth?

The acquisition is valued at $111 billion.

What did Paramount agree to in the settlement?

Paramount settled with 12 state attorneys general and the Writers Guild of America, committing to produce 30 films annually for two years (rising to 32 in years three through five), invest $1.5 billion in US film production over five years, and pay a $30 million penalty per film if it misses production targets.

When is the Warner Bros. Discovery deal expected to close?

The deal is targeted to close by October 1, 2026.

Why did states and the Writers Guild oppose the merger?

They raised concerns that combining two major studios would reduce production volume, cut competing buyers for scripts and talent, and eliminate jobs through overlapping-unit consolidation.

How is Paramount financing the acquisition?

Paramount is raising billions of dollars in additional debt specifically to fund the Warner Bros. Discovery side of the transaction.

For more on recent megadeals reshaping their industries, see our coverage of Nvidia’s $12.9 billion Hugging Face acquisition and the $1.65 billion deal reshaping cancer treatment’s supply chain.
Long-Term US Borrowing Costs Just Hit Their Highest Level Since 2004 — Here’s Why It Matters

A Treasury yields bond rout pushed long-term US borrowing costs to their highest level in more than two decades. The move came on September 24, 2026. It dragged stocks lower with it. The 30-year Treasury yield climbed to 5.438%, its highest point since 2004. The 10-year yield reached 5.11%, a level last seen in 2007. The S&P 500 closed at 7,664.35, down 0.54% on the day. The Dow Jones Industrial Average fell 0.72% to 51,139.63. The Nasdaq dropped 0.83% to 26,712.98.

What is driving the Treasury yields bond rout

Analysts pointed to strong economic data, not fresh inflation fears, as the main driver. Daniela Hathorn, senior market analyst at Capital.com, said “the economy may be capable of sustaining higher real interest rates than previously assumed.” She added that S&P Global reported the strongest business activity growth in more than five years. Capacity constraints are rising too. That combination is pushing real yields higher. It is a different, arguably more durable driver than the rate scares investors have grown used to over the past two years.

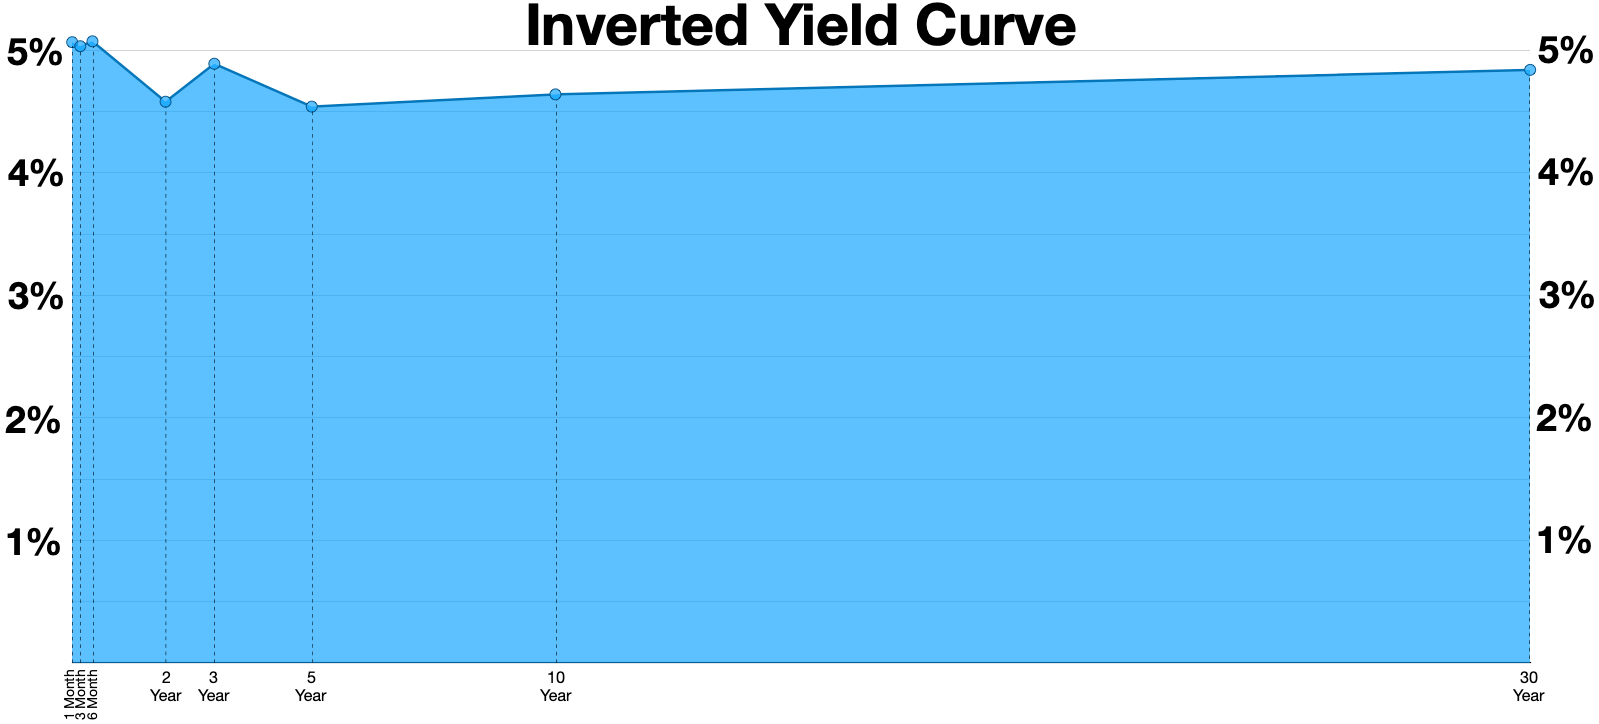
The 2-year yield, more sensitive to near-term Federal Reserve policy, rose to 4.897%. That is its highest level since 2023. The move came the same week the Fed raised its benchmark rate to a 3.75%-4.00% range. Markets now appear to be pricing in a longer stretch of elevated rates, not the rapid cuts some had expected earlier in the year. Oil added to the pressure. Crude futures jumped 3.95% to $95.80 a barrel, partly on Middle East energy concerns, feeding the same inflation-adjacent anxiety pushing yields higher.

Why higher yields hit stocks

US Treasury bond documents illustrating the Treasury yields bond rout

When long-term government bonds pay more, they compete directly with equities for investor money. They also raise the discount rate used to value future corporate earnings. Both effects make stocks look relatively less attractive. Technology and other high-growth sectors depend heavily on future earnings rather than current cash flow. They tend to feel this first. That pattern showed up on September 24: the Nasdaq’s 0.83% decline outpaced the broader S&P 500’s drop.

Who feels the Treasury yields bond rout beyond Wall Street

Rising long-term yields ripple well past trading floors. Mortgage rates, corporate borrowing costs and government debt-servicing costs are all tied to the same long end of the Treasury curve. That curve just hit a two-decade high. Companies planning to refinance debt or fund large capital projects now face a materially higher cost of capital than they did a few months ago. That includes the wave of AI data center spending covered elsewhere on this site, such as AMD’s push toward a trillion-dollar valuation.

What this means for household budgets

Higher long-term yields do not stay confined to bond trading desks. Mortgage rates in the US are priced off the 10-year Treasury yield, so a move to 5.11% tends to filter through to new home loans within days. Auto loans and other consumer credit follow a similar, if less direct, path. Credit card rates are tied more closely to the Fed’s short-term benchmark, which also rose this month. Renters and first-time buyers are likely to feel this first, since even a small rise in borrowing costs changes what a monthly payment looks like on a large loan. Companies that carry variable-rate debt face the same math on a larger scale.

What comes next for markets

Whether this is a temporary repricing or the start of a longer stretch of elevated rates depends largely on the activity data Hathorn cited. A run of soft economic reports could pull yields back down quickly. A continuation of the current trend could keep pressure on equity valuations well into the fourth quarter. Investors will be watching the next round of inflation and employment data. They will also watch for further signals from the Fed, following its September rate decision covered in our report on the Fed’s rate hike to 3.75%-4.00%. For how central banks elsewhere are responding, see our report on the Swiss National Bank’s latest decision.

Treasury Yields: Quick Questions Answered

What triggered the Treasury yields bond rout on September 24?

Stronger-than-expected business activity data and rising real interest rates, not fresh inflation fears, drove the move, according to Capital.com analyst Daniela Hathorn.

How high did Treasury yields actually go?

The 30-year yield reached 5.438%, its highest since 2004, and the 10-year yield hit 5.11%, its highest since 2007.

How did stocks react to the Treasury yields bond rout?

The S&P 500 fell 0.54%, the Dow fell 0.72%, and the Nasdaq fell 0.83% on September 24, 2026.

Does this mean the Federal Reserve will raise rates again?

The article does not report new Fed commentary tied to this specific move; the rout followed the Fed’s rate decision earlier in the same week.

Why do higher Treasury yields hurt growth stocks more?

Growth stocks are valued heavily on future earnings, and higher yields raise the discount rate used to value those future profits, making them look less attractive today.

What should businesses planning to borrow watch for next?

Continued strength in economic data could keep long-term borrowing costs elevated, while weaker data could pull yields back down.

Sources

Everyone Around Switzerland Is Raising Rates. It Just Sat Still

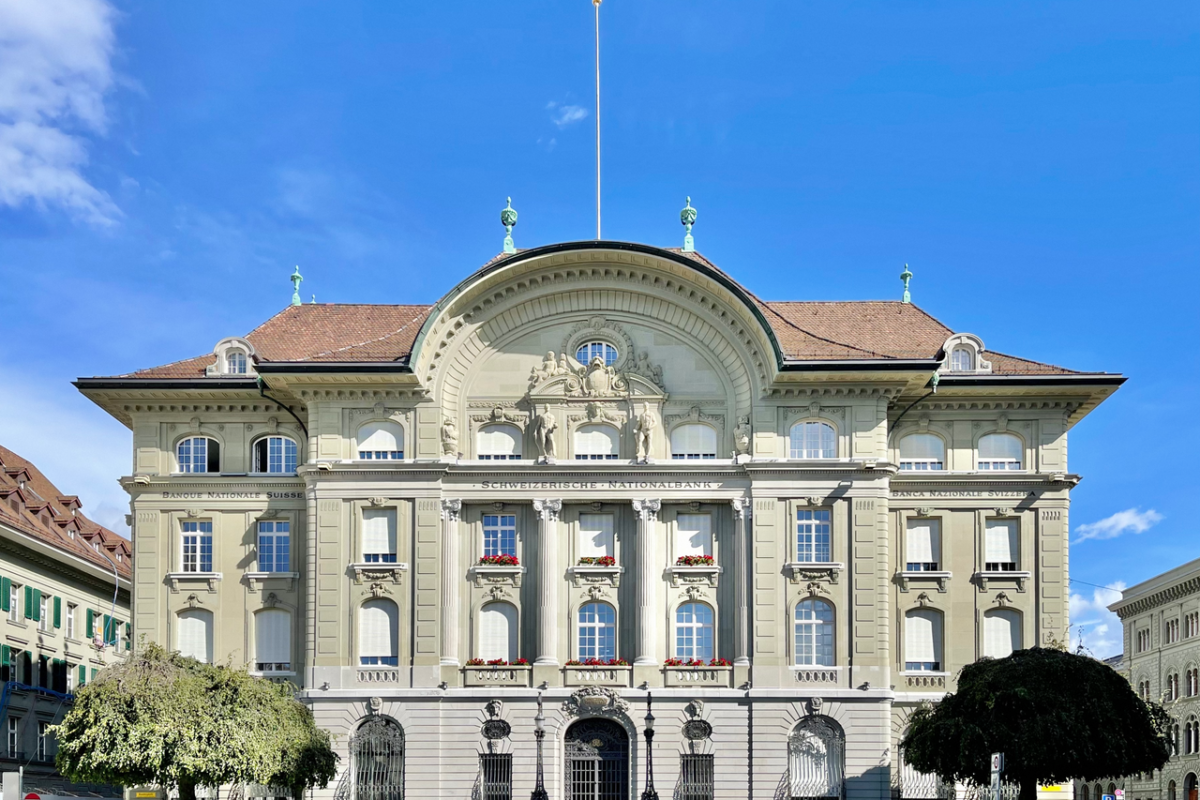
The Swiss National Bank left its policy rate at 0% on Thursday, 24 September 2026. The Swiss National
Bank decision
stands out because its neighbours went the other way. In its own statement, the SNB noted
that key rates were raised both in the euro area and in the US. Switzerland can afford to wait, for now,
because its inflation remains low.

What the Swiss National Bank decision kept in place

The policy rate stays at 0%. Banks’ sight deposits at the SNB earn that rate up to a threshold. Above
it, the discount remains 0.25 percentage points. The bank also repeated that it is willing to act in the
foreign exchange market as necessary. Those details come from the
SNB’s monetary policy assessment.

The SNB called its stance "appropriate" to keep inflation within the range it defines as price
stability. That range is 0% to 2%.

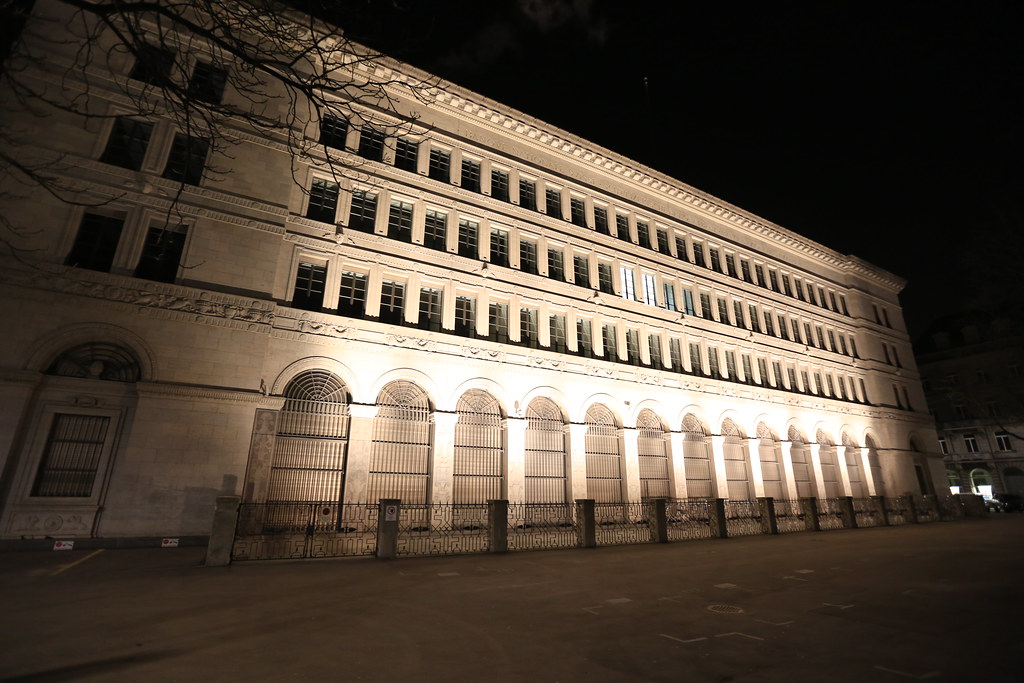
Swiss National Bank office in Zurich, one of the two seats behind the Swiss National Bank decision
The SNB runs head offices in Bern and Zurich.

The inflation picture behind the hold

Prices are rising, just slowly. Swiss inflation climbed from 0.6% in May to 0.8% in August. Goods
inflation turned positive in August for the first time since May 2024. Higher prices for oil products
drove most of that move.

The SNB expects inflation to rise a little further in the fourth quarter. It then sees it easing
during 2027 as energy inflation fades. Its conditional forecast reads:

  • 2026: 0.7% average inflation
  • 2027: 0.8%
  • 2028: 0.8%

That path stays inside the target band throughout. It assumes the policy rate holds at 0% over the
whole horizon. The bank said the medium-term forecast edged up partly because the Swiss franc has
weakened.

Why the Swiss National Bank decision diverges from the Fed and ECB

The contrast with other big central banks is the story. The US Federal Reserve raised its target range
to 3.75%-4.00% in September, its first hike since 2023, as CNBC reported.
Our coverage of the Fed’s rate hike explains
what drove that vote. The European Central Bank also tightened, as set out in our report on the
ECB interest rate hike.

Both face inflation above their 2% goals, much of it tied to energy. Switzerland does not. Its inflation
sits well below 1%. That gives the SNB room to hold while others squeeze.

A weaker franc helps the Swiss economy in the short run. The SNB said the recent depreciation is
having a supportive effect on growth.

The global backdrop matters here. The SNB noted that key rates rose in both the euro area and the US,
while inflation in many countries stayed above target on higher energy prices. Its own base case sees
moderate global growth ahead. It also sees inflation staying elevated for some time. That external picture
shapes how long Switzerland can keep its own rate at zero.

What the SNB expects for the Swiss economy

Second-quarter GDP growth was exceptionally strong. The SNB said an unusual surge in chemicals and
pharmaceuticals overstated the underlying pace. Even without it, growth was solid and broad-based.

There are soft spots. Capacity use sat below average, especially in manufacturing. Unemployment rose
again somewhat through early summer. The bank now expects growth of 1.5% to 2% for 2026, and around 1.5%
for 2027.

Where Swiss rates go from here

The SNB flagged the Middle East as the biggest risk. If energy prices end up significantly higher,
inflation would rise and growth would slow. Trade policy and exchange rates remain further sources of
uncertainty.

For savers and borrowers in Switzerland, little changes today. Mortgage and deposit rates tied to the
policy rate should stay near current levels. For currency watchers, the key variable is the franc. A much
weaker franc would push imported inflation up and test the 0% setting. The SNB holds its assessments
quarterly, so the next scheduled decision falls in December.

Swiss rate questions, answered

What did the Swiss National Bank decide?

On 24 September 2026 the SNB left its policy rate unchanged at 0%. The discount on sight deposits above the exemption threshold also stayed at 0.25 percentage points.

Why did the SNB hold while other central banks raised rates?

Swiss inflation is still inside the SNB’s 0-2% target range. It stood at 0.8% in August. The US Federal Reserve and the European Central Bank face inflation above target, which pushed them to hike.

What is the SNB’s inflation forecast?

The conditional forecast puts average inflation at 0.7% for 2026, 0.8% for 2027 and 0.8% for 2028. It assumes the policy rate stays at 0% throughout.

Will the SNB intervene in currency markets?

The SNB said it remains willing to be active in the foreign exchange market as necessary. It did not say whether it has intervened recently.

How fast is the Swiss economy growing?

The SNB expects growth of 1.5% to 2% in 2026 and around 1.5% in 2027. It said strong second-quarter GDP partly reflected an unusual boost from chemicals and pharmaceuticals.

What is the main risk the SNB flagged?

The situation in the Middle East. The SNB warned that energy prices could turn out significantly higher than expected, which would raise inflation and curb growth.

Sources

  • Swiss National Bank — Monetary policy assessment of 24 September 2026. snb.ch
  • CNBC — Fed rate decision September 2026: Rates rise to 3.75%-4%. cnbc.com

Images: featured photo by Robbie Conceptuel (CC0); in-article photo by TravelingOtter, licensed CC BY.

A $1.65 Billion Deal Just Reshaped Cancer Treatment’s Supply Chain

Australia’s Telix Pharmaceuticals agreed this week to buy Germany’s ITM Isotope Technologies Munich in a deal worth $1.65 billion upfront, one of the largest transactions yet in a radiopharmaceutical sector that has drawn heavy dealmaking interest in 2026. The Telix ITM acquisition deal could grow to as much as $2.35 billion including milestone payments, and it hands Telix a manufacturing and distribution network that reaches more than 65 countries.

Inside the Telix ITM acquisition deal

Telix will acquire all of ITM’s shares for $1.65 billion upfront, structured as $1.25 billion in Telix stock, $302 million in assumed net debt, and $96 million covering management equity rollovers and transaction expenses. On top of that, Telix could pay up to $700 million more in milestone payments tied to regulatory approvals, including US Food and Drug Administration clearance for ITM’s lead radiopharmaceutical asset. Telix is also taking on more than $300 million of ITM’s existing debt as part of the closing. Both boards have already approved the transaction, leaving customary regulatory sign-off as the main remaining step before the deal can be finalized.

What ITM brings to the table

ITM’s flagship candidate is ITM-11, a lutetium-177-based peptide receptor radionuclide therapy aimed at gastroenteropancreatic neuroendocrine tumors, a rare and difficult-to-treat form of cancer. The drug has completed its Phase 3 COMPETE trial, and a second Phase 3 study, COMPOSE, is fully enrolled with an interim analysis expected in the first half of 2027. ITM’s manufacturing infrastructure and distribution network covering more than 65 countries was central to Telix’s rationale for the deal.

Why this counts as radiopharma consolidation

The transaction is part of a broader wave of dealmaking in radiopharmaceuticals this year, as larger companies race to secure manufacturing capacity and late-stage pipeline assets rather than build them from scratch. Telix has described the combined company as a “vertically integrated radiopharmaceutical company,” language that signals an intent to control everything from isotope production to distribution rather than relying on partners at each stage.

Telix ITM acquisition deal

What happens before the deal closes

Telix and ITM expect to close the transaction by the end of 2026, with Telix shareholders set to hold about 76.3% of the combined company and ITM’s backers holding roughly 23.7%. The combined entity is projected to generate more than $1.3 billion in unaudited revenue and income this year, a scale that puts it in direct competition with larger players already established in nuclear medicine.

How the deal was structured to limit dilution

Telix’s decision to fund most of the upfront payment in its own stock, rather than cash or new debt, was a deliberate choice to preserve balance-sheet flexibility while still meeting ITM shareholders’ price expectations. The $302 million in assumed net debt and $96 million covering equity rollovers and transaction costs round out a structure that leaves Telix with room to continue funding its existing commercial pipeline without a major capital raise. Analysts noted that the roughly 76.3%-23.7% post-close ownership split gives ITM’s existing investors meaningful upside if the combined company’s stock performs well, an arrangement that made the deal easier to negotiate than an all-cash buyout might have been.

Why radiopharma consolidation is accelerating in 2026

Radiopharmaceuticals sit at an unusual intersection of nuclear physics, oncology and complex cold-chain logistics, since many of the isotopes involved decay within days and must move from production facility to hospital on tight schedules. That complexity has made manufacturing scale and distribution networks, rather than just drug pipelines, a competitive advantage in their own right, which helps explain why larger players have increasingly chosen to acquire established manufacturers like ITM rather than build equivalent infrastructure from scratch. Novartis and other established nuclear medicine players have made similar moves in recent years, and Telix’s acquisition of ITM is widely read as a direct response to that competitive pressure.

What analysts are watching next

Investor reaction to the announcement was mixed in early trading, with some analysts flagging integration risk given the scale of the combination, while others highlighted the strategic logic of pairing Telix’s existing commercial products with ITM’s manufacturing depth. The interim analysis of ITM’s COMPOSE trial, expected in the first half of 2027, will be an early test of whether the acquired pipeline delivers on its promise, and regulators in multiple jurisdictions will need to sign off before the companies can finalize the transaction as planned.

Frequently Asked Questions

How much is the Telix ITM acquisition deal worth?

Telix Pharmaceuticals is paying $1.65 billion upfront for Germany’s ITM Isotope Technologies Munich, with up to $700 million more in milestone payments tied to regulatory approvals.

What does ITM make?

ITM’s lead asset is ITM-11, a lutetium-177-based radiopharmaceutical designed to treat gastroenteropancreatic neuroendocrine tumors, a rare form of cancer.

How is the deal being paid for?

The upfront payment combines $1.25 billion in Telix shares, $302 million in assumed net debt, and $96 million covering management equity rollovers and transaction costs.

When is the deal expected to close?

Telix and ITM expect to close the transaction by the end of 2026, subject to standard regulatory approvals.

Who will own the combined company?

Telix shareholders will hold about 76.3% of the combined entity, with ITM’s existing backers holding roughly 23.7%.

Related coverage on Tamara News

For more context, see our reporting on Nscale ipo filing and Dangote refinery ipo.

Sources