One Cyberattack, 14 Lawsuits: Inside the Insurer That Credit Unions Are Now Suing

TruStage Financial Group now faces at least 14 lawsuits after a cyberattack it disclosed on July 15, 2026. The Madison, Wisconsin insurer sells life and auto coverage through credit unions nationwide. The TruStage outage lawsuits include one filed by a credit union and roughly a dozen more brought by individual policyholders. Most seek class-action status, according to American Banker.

Bessemer System Federal Credit Union in Greenville, Pennsylvania filed the first suit on July 17. It alleges TruStage failed to implement adequate, industry-standard cybersecurity safeguards. The credit union says that failure led directly to the outage and its own financial losses. TruStage shut down its own network to contain the attack. The company still has not determined whether member or employee data was exposed, per CU Today.

What the TruStage outage lawsuits allege

Federal court records reviewed by American Banker show at least 13 of the lawsuits landed in the Western District of Wisconsin, where TruStage is headquartered. The suits generally argue the company failed to protect systems and data to industry standards. They say the resulting outage disrupted payment processing and account access for weeks. Bessemer’s complaint focuses on recovering costs the outage imposed on the credit union’s own operations, not data-exposure damages.

Individual policyholder suits instead center on the risk that personal data was compromised. TruStage has not confirmed a breach of member information. That distinction matters procedurally. Courts often require plaintiffs to show concrete harm, not just risk, before a data-breach class action can proceed.

TruStage is not a small niche vendor. It supplies life insurance, auto coverage, retirement products, and payment protection to a large network of credit unions nationwide. Its outage did not stay contained to one institution’s members. Credit unions that bundle TruStage products directly into member accounts had little room to route around the failure. Their insurance and payment-protection functions were not duplicated anywhere else in their own systems. Plaintiffs’ attorneys point to that structural dependency when arguing the company should have invested more in redundancy and security before the attack.

Weeks of missed payments and frozen funds
Credit union office affected by the TruStage outage lawsuits following the July cyberattack

The outage’s practical impact extended well beyond TruStage’s own systems. CU Today reported that missed payments and frozen funds persisted six weeks after the attack. That affected credit unions relying on TruStage for payment protection and insurance products bundled into member accounts. TruStage has since said its recovery is “gaining ground” but that it has “not reached the finish line.” That is an unusually candid public update for a company facing active litigation.

Why one vendor’s outage hits so many credit unions

TruStage’s business model concentrates risk. It supplies insurance and payment-protection products to a large network of credit unions, rather than operating as one institution’s internal system. When its network went down, the disruption cascaded to every credit union relying on those products. That is part of why the lawsuit count climbed so quickly. Credit unions, unlike large banks, often lack the in-house resources to quickly substitute a failed vendor’s function.

What happens next in the TruStage litigation

The Western District of Wisconsin cases will likely be consolidated for pretrial proceedings, given their overlapping claims. That is a common step in multi-plaintiff data-incident litigation. TruStage has not indicated a settlement timeline. It still has not confirmed whether member data was exposed, a determination that could significantly affect the individual plaintiffs’ claims once resolved.

Insurers generally face separate state reporting obligations once they confirm a cybersecurity incident, obligations that run independent of civil litigation. Those requirements could add regulatory scrutiny on top of whatever the lawsuits eventually produce, though TruStage has not said whether any state insurance regulator has opened a formal inquiry. For now, the credit unions caught in the middle are left absorbing member complaints about an outage they did not cause and cannot fix on their own, since the failure sits inside a shared vendor’s systems rather than their own.

The incident is likely to become a reference point for credit unions evaluating their own vendor risk. Smaller institutions often rely on a handful of outside providers for insurance, payments, and core banking functions. That concentrates risk in a way large banks, with more in-house capacity, typically avoid. Whether the lawsuits change how vendors like TruStage structure their contracts and security spending remains an open question that will likely take the litigation itself to answer.

Frequently asked questions

What is TruStage?
TruStage is a Madison, Wisconsin-based financial group that sells life and auto insurance, retirement accounts, and payment protection products through credit unions.

How many lawsuits has TruStage faced?
At least 14 as of early September 2026, including one from a credit union and roughly a dozen from individual policyholders.

Was member data exposed in the attack?
TruStage has said it has not yet determined whether member or employee data was compromised.

When did the cyberattack happen?
TruStage disclosed the incident publicly on July 15, 2026, after shutting down its own network to contain it.

Where are the lawsuits being heard?
At least 13 of the 14 suits were filed in the US District Court for the Western District of Wisconsin, where TruStage is headquartered.

Related coverage

Sources

  • American Banker — CU vendor TruStage faces 14 suits over monthslong outage. americanbanker.com
  • CU Today — TruStage Says Cyberattack Contained, But Data Answers Could Still Be Months Away. cutoday.info
  • CU Today — Missed Payments, Frozen Funds Persist Six Weeks After TruStage Cyberattack. cutoday.info

Every Memory Chip Apple, Nvidia and Samsung Will Need Next Year Is Already Gone

Samsung, SK Hynix, and Micron have sold out their entire 2027 memory chip production capacity. Industry reports confirmed the sellout in early September 2026. The memory chip shortage 2027 covers both DRAM and the high-bandwidth memory, known as HBM, that powers AI accelerators. Customers are being allocated only 60% to 70% of the volumes they requested, according to Tom’s Hardware.

All memory capacity the three companies plan to manufacture in 2027 is booked. No additional supply is planned beyond what customers already reserved, according to TweakTown. Final pricing for 2027 orders will be set closer to delivery. So much capacity is being locked in years ahead of manufacturing that early prices remain provisional.

Why the memory chip shortage 2027 is different from past cycles

Memory chip shortages and gluts have cycled through the industry for decades. Usually they track swings in PC and smartphone demand. This shortage traces to a different driver. Artificial intelligence hyperscalers are buying enormous quantities of HBM to build AI accelerators. They are signing long-term agreements to guarantee supply years in advance. That demand pattern leaves little room for the usual boom-bust cycle. AI infrastructure buildouts show no sign of slowing through 2027.

Samsung led the DRAM market in the second quarter of 2026, with 39% share. SK Hynix followed at 26%, and Micron held 25%. That data comes from Seeking Alpha. Those three companies control most of global memory production. That is part of why their capacity decisions ripple through the entire electronics industry at once.

Who gets squeezed when memory sells out

Semiconductor fabrication facility linked to the memory chip shortage 2027

Companies that build AI servers, smartphones, laptops, and other memory-dependent devices now face a choice. They can accept smaller allocations than they requested. They can pay higher prices for whatever capacity remains. Or they can delay product plans that depend on memory they cannot secure. Smaller device makers without long-term supply agreements are likely to feel the squeeze hardest. Major hyperscalers and top-tier smartphone brands typically get priority in allocation negotiations.

The wider DRAM market, beyond the AI-focused HBM segment, is also tightening as a result. PC and smartphone makers compete with AI infrastructure buyers for the same DRAM production lines. Their own demand has not spiked the way AI demand has, but they are seeing tighter supply anyway.

What this means for device prices

Memory is a core input cost for nearly every modern electronic device, from phones to laptops to data center servers. When supply tightens this severely, manufacturers typically pass at least part of the higher cost on to buyers. Consumers may not see price increases immediately. Many device makers hold existing component inventory and locked-in pricing agreements that take months to work through. Analysts expect the clearest price pressure to show up in 2027. That is when older, cheaper memory contracts expire and manufacturers must buy at the new, tighter market rates.

What happens next in the memory market

Samsung, SK Hynix, and Micron have not announced plans to add new manufacturing capacity beyond what is already sold out for 2027. Building new fabrication plants takes years and enormous capital investment, so a quick fix is not realistic. Analysts consider 2027 likely to be the most difficult phase of the shortage. Continued tightness beyond that remains possible if AI infrastructure spending keeps growing at its current pace. Companies still trying to lock in 2027 supply at this point are largely out of options, since allocation decisions are already made.

The shortage also touches consumer electronics that have nothing to do with AI directly. Game console makers, camera manufacturers, and budget smartphone brands all compete for the same DRAM and NAND flash production lines that AI buyers are squeezing. That broader reach is one reason analysts are watching this shortage more closely than past memory cycles. Earlier cycles usually stayed contained to a narrower slice of the electronics supply chain, rather than spreading across nearly every device category at once.

Frequently asked questions

What is the memory chip shortage 2027?
Samsung, SK Hynix, and Micron have sold out their entire 2027 DRAM and HBM production capacity. AI hyperscalers securing long-term supply agreements are the main driver.

Why is AI driving the memory shortage?
AI hyperscalers need huge quantities of high-bandwidth memory to build AI accelerators. They are signing multi-year agreements to guarantee supply, leaving little spare capacity for other buyers.

How much of their requested supply are customers getting?
Reports indicate customers are being allocated only 60% to 70% of the volumes they originally requested.

Which companies control most memory chip production?
Samsung, SK Hynix, and Micron together control the large majority of global DRAM and HBM production. Samsung led with 39% DRAM market share in Q2 2026.

Will device prices rise because of this shortage?
Analysts expect price pressure to build through 2026. It should become most visible in 2027, once manufacturers work through existing inventory and older pricing agreements.

Related coverage

Sources

  • Tom’s Hardware — Samsung and SK hynix warn AI-driven memory shortages could last until 2027 and beyond. tomshardware.com
  • TweakTown — Memory capacity for all of 2027 has reportedly been booked and sold. tweaktown.com
  • Seeking Alpha — Samsung, SK Hynix, Micron sell out 2027 memory chip supply: report. seekingalpha.com

Oracle, Adobe and Kroger Report Days Before the Fed Decides Rates

Wall Street is heading into a stretch that could set the tone for the rest of the quarter. The September earnings week preview covers a run of reports from Oracle, Adobe and Kroger. They arrive just as investors weigh a hot August jobs report against a Federal Reserve meeting only days away.

Oracle and Adobe both report on September 10, followed by Kroger on September 11. That gives markets a cross-section of enterprise software demand and consumer spending health in a single week. Each report lands against a backdrop of markets already on edge after Treasury yields hit a 20-month high earlier this month.

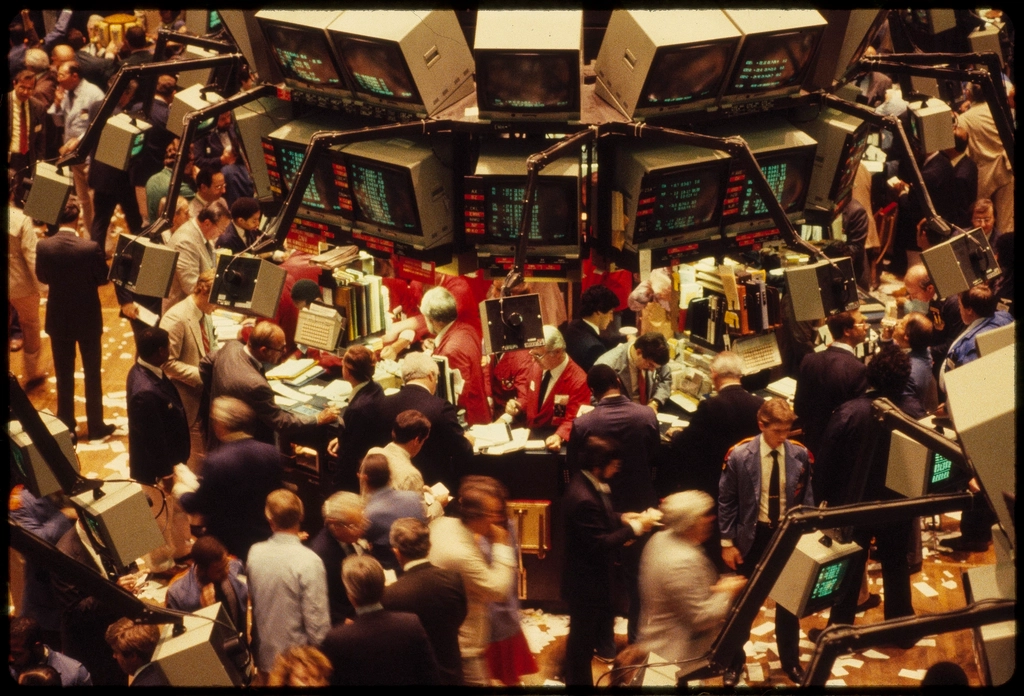
Historic stock exchange scene tied to this September earnings week preview

What to watch in this September earnings week preview

Oracle’s results will draw particular attention to its cloud infrastructure business. Investors have scrutinized this area closely across the sector this year, testing whether heavy artificial intelligence spending is translating into durable revenue growth rather than one-time buildouts. Analysts are watching backlog figures and cloud bookings as closely as the headline revenue number.

Adobe’s report will offer a read on enterprise software demand and subscription growth. That segment has faced pressure from questions about how generative AI tools might eventually compete with or complement Adobe’s own creative and marketing software products.

Kroger’s results provide a different lens entirely: consumer spending at the grocery level. That area is sensitive to both inflation and the broader health of household budgets. A strong or weak print from Kroger tends to move consumer staples stocks more broadly. Investors watch grocery spending closely as a proxy for household financial pressure.

Why this week matters more than a typical earnings cycle

This round of reports lands just days before the Federal Reserve’s September 15-16 meeting. Market pricing has shifted toward a real possibility of a rate move after a stronger-than-expected August jobs report. Earnings that beat or miss expectations this week could shift how investors read the Fed’s incoming decision.

Bond markets have already been volatile, with yields touching multi-month highs before pulling back slightly in early September. Equity investors are watching whether that yield volatility spills into how the market prices this week’s earnings. Higher borrowing costs can weigh more heavily on richly valued technology and software names like Oracle and Adobe.

What analysts are forecasting

Consensus estimates going into the reports reflect continued double-digit cloud growth expectations for Oracle. Adobe’s core subscription business carries more modest single-digit growth expectations. Kroger’s guidance will be watched closely for any commentary on how tariff-related cost pressures or grocery price inflation are affecting margins heading into the holiday shopping season.

Options market pricing ahead of the reports suggests investors are bracing for above-average volatility in Oracle shares specifically. That reflects how sensitive the stock has become to any signal about the durability of AI-driven cloud demand.

What happens after this week’s reports

However these three companies perform, their results will feed directly into the market narrative heading into the Fed’s rate decision the following week. A run of strong results could reinforce the case for a more hawkish Fed stance. Weaker consumer or enterprise spending signals could instead bolster arguments for the central bank to hold steady.

How last week’s earnings set the stage

The lead-up to this week’s reports was shaped by a mixed batch of results. GitLab surged roughly 20% after its latest quarterly numbers beat expectations. Broadcom fell after investors reacted negatively to its fourth-quarter revenue forecast and operating margin projections. That split reaction shows how selectively markets are rewarding growth this earnings season.

Major indexes have still managed modest gains through early September. The S&P 500 and Nasdaq both notched small advances even as Treasury yields climbed. That combination suggests investors will look past bond market volatility as long as earnings keep validating current valuations. This week’s reports will test that directly.

What smaller investors should watch for

Retail investors without direct positions in Oracle, Adobe or Kroger still feel the ripple effects. Broad market index funds hold all three companies. Sharp moves in their share prices show up in retirement accounts even for people who never picked individual stocks. Financial advisors generally recommend against reacting to single-week earnings swings, since one report rarely changes a company’s long-term trajectory on its own.

Sector-wide reaction matters more than any single stock. If cloud and software names sell off broadly after Oracle and Adobe report, that often signals a shift in how investors price risk. The shift usually spans the whole technology sector, not just those two companies.

Frequently asked questions

Which companies report earnings this week?
Oracle and Adobe report on September 10, followed by Kroger on September 11, as part of this September earnings week preview.

Why does Oracle’s report matter so much to markets?
Oracle’s cloud infrastructure results are seen as a bellwether for whether heavy AI-related spending across the sector is translating into durable revenue growth.

How does Kroger’s report relate to inflation?
Kroger’s grocery-level results offer a read on consumer spending health and cost pressure at the household level, closely watched as an inflation proxy.

How does this earnings week connect to the Fed’s decision?
Results from all three companies land just days before the Fed’s September 15-16 meeting, and could shift how markets price the odds of a rate move.

For more on the market backdrop heading into this week, see our coverage of the hot jobs report rattling rate-cut hopes and the earnings surge that lifted GitLab’s market value.

Sources

  • Kiplinger — Earnings Calendar and Analysis for This Week (September 7-11). kiplinger.com
  • CNBC — Stock market news for Sept. 2, 2026. cnbc.com
  • Charles Schwab — Hot Jobs Report Hurts Stocks, Lifts Rate Hike Odds. schwab.com

OPEC+ Just Held Steady on Oil — Prices Are Rising Anyway

OPEC+ decided on September 6 to leave its production policy unchanged for October. It is a quiet decision that still carries outsized weight for drivers and businesses worldwide. The OPEC October oil output call means the group will not add extra barrels to the market next month. That comes even as fighting between the United States and Iran keeps pushing prices higher.

Crude climbed more than 7% over the past week after Washington and Tehran resumed military exchanges. US diesel prices touched a record high in the same stretch. Against that backdrop, OPEC+ chose to hold steady rather than open the taps further.

Crude oil barrels tied to the OPEC October oil output decision

What the OPEC October oil output decision actually changes

The group had already been unwinding a long-standing 1.65 million-barrel-a-day supply cut agreed in 2023. It added output gradually through most of this year. August’s meeting completed that phased rollback. Supply policy is now back to something closer to normal for the alliance’s core members.

By holding steady for October, the seven core OPEC+ members are signaling caution rather than confidence. Those members are Saudi Arabia, Russia, Iraq, Kuwait, Algeria, Kazakhstan and Oman. Analysts read the pause as an acknowledgment that prices are already rising on their own because of the conflict. Extra supply announcements are less urgent than they would otherwise be.

Why the group’s power over prices is more limited than usual

OPEC+ can change production targets on paper. It cannot guarantee those barrels actually reach the market, particularly while fighting disrupts exports through the Strait of Hormuz. Group members, including Russia, are already producing well below their stated targets because of the war’s effect on shipping and infrastructure.

That gap between announced policy and real-world output has widened this year, according to analysts tracking the group’s compliance. It means this week’s decision matters less as a lever on prices. It matters more as a signal of how the group’s most influential members are reading the security situation in the Gulf.

What this means for prices at the pump

US diesel prices hit a record high in the same week as the OPEC decision. That raises costs for freight, agriculture and any business that depends on trucking. Consumers are likely to see the effects first in fuel prices. A sustained rise also tends to filter into shipping costs and eventually retail prices for goods that travel by truck or ship.

Energy analysts caution that the size of the effect depends heavily on how long the US-Iran exchanges continue. A short-lived flare-up would likely fade from pump prices within weeks. A prolonged disruption to Gulf shipping routes would keep upward pressure on fuel costs for longer.

What happens next for oil markets

OPEC+ meets again before its November output decision. Members will watch both the security situation in the Gulf and demand signals from major economies before deciding whether to resume adding supply. A ceasefire or de-escalation between the US and Iran would likely ease pressure on prices regardless of what the group decides.

Traders are also watching US strategic reserve policy. They are watching whether major consuming nations take any coordinated steps to offset the price pressure, something that has happened during past periods of Gulf-related supply anxiety.

How markets are reading the decision

Traders had gone into the meeting split on strategy. Would OPEC+ reassert influence over prices by adding supply, or step back and let the security premium run its course? The decision to hold steady suggests the group’s core members would rather avoid the appearance of flooding the market during active fighting.

Options markets tied to crude futures showed increased hedging activity in the days after the announcement. That signals traders expect continued volatility rather than a quick return to calmer pricing. Airlines, shipping companies and manufacturers are watching closely, since sustained price increases erode margins that are hard to pass on to customers quickly.

Freight operators in particular have flagged fuel surcharges as a near-term risk. Diesel costs feed directly into shipping rates on both trucking and maritime routes. Retailers that depend on predictable logistics costs are watching the situation closely heading into the final quarter of the year.

Frequently asked questions

What did OPEC+ decide about October oil output?
OPEC+ agreed to keep its production policy unchanged for October rather than adding further barrels, following a phased supply increase completed in August.

Why are oil prices rising despite steady OPEC+ output?
Prices climbed more than 7% in a week after renewed US-Iran military exchanges disrupted shipping confidence, separate from any OPEC+ decision.

Does OPEC+ control prices directly?
Not entirely. The group sets production targets, but members like Russia already produce below those targets because of the war’s effect on exports through the Strait of Hormuz.

Will gas prices keep rising?
That depends largely on how long the US-Iran exchanges continue. A short flare-up would likely fade quickly, while a longer disruption would sustain higher prices.

For more on how the Gulf conflict is affecting global trade, see our coverage of the tanker attacks in the Strait of Hormuz and our earlier report on bond yields and the oil price surge.

Sources

  • CNBC — OPEC+ keeps oil output policy unchanged for October. cnbc.com
  • Al Jazeera — OPEC+ countries say they will expand monthly oil production. aljazeera.com
  • U.S. Energy Information Administration — Short-Term Energy Outlook. eia.gov

Broadcom’s Numbers Were Great — Except the One That Mattered Most

Broadcom shares fell more than 2.5% in extended trading this week. The chipmaker issued a fourth-quarter revenue outlook that landed just below what Wall Street expected. The Broadcom Q4 revenue forecast called for roughly $34.8 billion. Analysts had averaged estimates near $35.03 billion, according to the Globe and Mail.

Why the Broadcom Q4 revenue forecast disappointed investors

The shortfall was small in percentage terms. But it arrived alongside signals of intensifying competition in custom AI processors. That segment is what investors have leaned on most to justify Broadcom’s valuation. Investing.com reported the soft guidance overshadowed otherwise strong growth elsewhere in the business. That pattern has repeated across several AI-linked chip names this earnings season.

Broadcom Q4 revenue forecast
Custom AI processors have become the fastest-growing and most closely watched part of Broadcom’s business.

Broadcom’s own numbers were not weak in isolation. Fourth-quarter consolidated revenue is still projected to grow 93% year over year to that $34.8 billion figure. The company also expects to hold its non-GAAP operating margin at 66%, a level most industrial companies would consider exceptional.

The AI chip business is still growing fast

Broadcom expects AI semiconductor revenue to accelerate to $21.7 billion in the fourth quarter. That is up 236% year over year. This growth rate outpaces the company’s overall revenue growth by a wide margin. It underscores how central custom AI chips have become to Broadcom’s near-term story, even as headline guidance missed estimates.

What “below estimates” actually means here

A guidance miss of roughly $230 million on a $34.8 billion forecast is a rounding error in absolute terms. But stock prices react to the gap between expectation and reality, not the underlying scale. Analysts had priced in near-flawless execution from Broadcom’s custom silicon business. Any signal of rising competition was always going to move the stock more than the raw numbers suggest.

The quarter ahead

Broadcom’s next earnings report will answer a key question. Does the softer guidance reflect a one-quarter blip from customer order timing? Or is it an early sign that rivals are winning a larger share of custom AI chip contracts? Investors will watch commentary on customer concentration closely. Broadcom’s custom processor business depends on a small number of very large cloud computing customers rather than a broad base.

Semiconductor peers reporting later this month will offer an early read on whether Broadcom’s guidance miss reflects an industry-wide slowdown in custom chip orders or a company-specific issue.

Why analysts prize this one number

Wall Street has treated Broadcom’s custom AI chip guidance as a proxy for the entire custom silicon industry this earnings season. That is why a modest miss triggered an outsized stock reaction. Investors are not just pricing Broadcom’s own results. They are using this number to guess how fast big cloud providers plan to keep spending on custom processors instead of buying off-the-shelf chips from rivals.

Several major cloud customers design chips jointly with Broadcom under multi-year agreements. Any sign those customers are slowing orders, even slightly, ripples through the stock faster than the dollar figures alone would suggest. That is the real story behind Wednesday’s drop.

By most historical standards, this remains a strong quarter for Broadcom. Investors, for now, appear more focused on the trend line in custom chip orders than on the overall scale of the business.

Large options positions often build up ahead of major chip earnings. That kind of positioning can amplify price swings in either direction once results land, which helps explain why a relatively modest guidance gap can produce an outsized move in a stock like Broadcom’s.

Broadcom’s next report will land after a full quarter of the AI chip market’s current competitive dynamics play out. That report, more than this week’s reaction, will show whether Wednesday’s guidance was conservative positioning or an early signal of a genuine slowdown.

Rival chipmakers reporting in the meantime will offer an earlier read on whether the caution is industry-wide or specific to Broadcom’s customer mix. Investors will parse those results closely for hints before Broadcom reports again.

Until then, Wednesday’s reaction stands as a reminder of how thin the margin for error has become at the top of the AI chip trade. Even a strong quarter is not enough on its own if guidance falls short of a very high bar.

That bar keeps rising each quarter, set less by Broadcom itself than by how aggressively the broader AI infrastructure buildout keeps accelerating around it.

Fast facts and FAQs

Why did Broadcom stock fall after earnings?

Broadcom issued fourth-quarter revenue guidance of about $34.8 billion. That was below the roughly $35.03 billion analysts expected, sending shares down more than 2.5% in extended trading.

Is Broadcom’s AI chip business still growing?

Yes. The company expects AI semiconductor revenue to reach $21.7 billion in the fourth quarter, up 236% from a year earlier.

What is Broadcom’s expected profit margin?

Broadcom expects to maintain a non-GAAP operating margin of 66% in the fourth quarter.

How much revenue growth is Broadcom still forecasting?

Overall fourth-quarter revenue is projected to grow 93% year over year despite missing the specific dollar estimate analysts had modeled.

What is driving concern about Broadcom’s custom chip business?

Reports point to intensifying competition in custom AI processors as the reason behind the softer-than-expected guidance.

Sources

  • The Globe and Mail — Broadcom forecasts quarterly revenue below estimates, signalling intense competition. theglobeandmail.com
  • Investing.com — Broadcom slips as soft Q4 guide overshadows strong growth outlook. investing.com

Related coverage on Tamara News: Nvidia’s Hugging Face acquisition and Anthropic’s Nvidia compute deal.