Dave & Buster’s Stock Just Fell Off a Cliff — Here’s Why

Shares in Dave & Buster’s Entertainment tumbled more than 12% on September 15, 2026. The arcade and restaurant chain badly missed Wall Street’s revenue and profit targets for the quarter.

The Dave & Buster’s earnings miss centers on a swing from an expected profit to an unexpected loss. Analysts had forecast a profit of 18 cents a share. The company instead posted an adjusted loss of 27 cents a share.

How far Dave & Buster’s missed its targets

The company reported quarterly revenue of $544.1 million. That’s below the $556.8 million analysts had expected. Adjusted EBITDA came in at $98.9 million, well short of the $120.4 million consensus estimate.

That combination points to more than soft sales. Costs are also squeezing margins on top of weaker customer traffic.
Dave & Buster's earnings miss

What’s behind the Dave & Buster’s earnings miss

Dave & Buster’s depends on discretionary spending. Families and young adults choose to spend on games, food and drinks rather than save it. That kind of spending is usually first to slow when consumers grow cautious.

The chain has leaned on remodeled locations and new game formats to draw repeat visits. This quarter’s numbers suggest that strategy hasn’t offset softer overall demand.

How investors reacted

The stock’s double-digit drop reflects how sharply results diverged from expectations. A 2% revenue miss alone wouldn’t normally move a stock this much. Combined with an unexpected loss, it changed the market’s read on the company’s trajectory.

The reaction also landed in a week when broader US markets were jittery over the Federal Reserve’s looming rate decision. That left little patience for consumer names that disappoint.

What happens next for Dave & Buster’s

Management will face pressure on its next earnings call. It will need to explain whether the shortfall reflects a temporary dip in foot traffic, or a deeper shift in consumer spending.

Investors will also watch whether the chain adjusts promotional pricing or slows new location openings after this weaker quarter.

How this fits the wider consumer picture

Dave & Buster’s results land alongside other early-September earnings misses from consumer-facing companies. That adds to a picture of households pulling back on nonessential spending, even as headline employment holds up.

Retail analysts will watch whether other leisure and entertainment chains report similar softness in the coming weeks. That would suggest the pullback goes beyond one company’s execution.

What this means for anyone holding the stock

A single bad quarter doesn’t automatically signal a longer decline. But it does raise the bar for the next report to show a clear turnaround.

Anyone holding shares through this drop should watch same-store sales closely. That metric strips out new store openings and gives a cleaner read on whether existing locations are recovering.

How rivals in the sector are faring

Other out-of-home entertainment chains have faced similar pressure this year, as households trim discretionary outings in favor of cheaper at-home options.

A pattern across the sector, rather than a single company’s stumble, would tell a different and arguably more worrying story about consumer confidence heading into the final months of the year.

What analysts will ask on the next earnings call

Expect pointed questions about foot traffic trends by region, and whether the loss came from one-time costs or an ongoing pricing problem.

How clearly the company answers those questions will likely matter more to the stock than the headline numbers themselves.

Frequently asked questions

Why did Dave & Buster’s stock drop?

Shares fell more than 12% on September 15, 2026, after the company reported revenue and earnings well below Wall Street’s expectations, including an unexpected quarterly loss.

How much revenue did Dave & Buster’s report?

The company reported $544.1 million in quarterly revenue, short of the $556.8 million analysts had forecast.

Did Dave & Buster’s turn a profit?

No. The company posted an adjusted loss of 27 cents per share, compared with analyst expectations of an 18-cent profit.

What does this say about consumer spending?

Discretionary entertainment spending, like arcade visits and out-of-home dining, is often among the first areas consumers cut back on when they grow more cautious, which may explain the softer traffic.

Is this the first earnings miss for the company this year?

This article covers the results reported on September 15, 2026; it does not compare against earlier quarters in detail.

Related coverage on Tamara News

Sources

The ECB Just Made Borrowing More Expensive Across Europe

The European Central Bank’s new, higher interest rates take effect across the eurozone on September 16, 2026. Policymakers voted for a second hike this year to fight inflation tied to the Israel-Iran conflict.

The ECB interest rate hike lifts the deposit facility rate by 25 basis points, to 2.50%. The main refinancing rate rises to 2.65%. The marginal lending facility rises to 2.90%. The ECB’s Governing Council made the call on September 10.

Why the ECB raised rates again

The ECB says conflict in the Middle East keeps pushing up energy costs across the eurozone. Its staff now expect headline inflation to average 3.0% in 2026. That’s well above the bank’s 2% target.

Policymakers had already raised rates once earlier this year. A second increase suggests the Governing Council sees this inflation spike as more than a one-off energy shock.

ECB interest rate hike

What the ECB’s updated forecasts show

ECB staff also revised inflation forecasts for 2027 and 2028 upward, to 2.5% and 2.1%. Growth forecasts rose too: 0.9% for 2026 and 1.4% for 2027.

Those upgrades suggest the ECB expects the eurozone economy to hold up despite rising borrowing costs. But inflation is now set to stay above target longer than earlier projected.

How the ECB interest rate hike compares with other central banks

The Federal Reserve has signaled it may raise US rates for the first time since 2023. It cites similar energy-driven inflation from the same Middle East conflict.

The Bank of England’s Monetary Policy Committee is due to announce its own decision on September 17. That’s a day after the ECB’s new rates took hold, keeping major central banks on a similar path this month.

Who feels the ECB interest rate hike first

Variable-rate mortgage holders across the eurozone usually notice first. Many home loans in Spain and Portugal are tied directly to benchmark rates that move with ECB policy.

Small businesses that rely on short-term credit will also face higher financing costs. Many are already managing higher energy bills tied to the same conflict driving the inflation numbers.

How this hike differs from the first one this year

The ECB’s earlier hike this year came as a preemptive move against rising energy prices. This second increase responds to inflation that has already climbed above forecast.

That shift, from acting ahead of inflation to reacting to it, is itself a signal. It suggests policymakers see less room to wait out the current shock than they did earlier in the year.

How markets reacted to the ECB interest rate hike

The euro firmed slightly against the dollar in the days after the decision. Traders priced in a central bank willing to keep raising rates even as growth forecasts improved.

Eurozone government bond yields also ticked higher. That reflects expectations that borrowing costs will stay elevated longer than markets had assumed earlier this year.

What happens next for borrowers and savers

Higher ECB rates typically feed into mortgage and business lending costs within weeks. Savings and deposit rates tend to rise more slowly.

The Governing Council’s next meeting will show whether this is the peak for the cycle. Persistent inflation from the Iran conflict could push it toward a third hike before year-end.

Frequently asked questions

What is the ECB’s new deposit rate?

The European Central Bank’s deposit facility rate rose to 2.50% from September 16, 2026, up from 2.25% previously, after a 25 basis point hike decided on September 10.

Why did the ECB raise interest rates?

The ECB cited inflation pressure from the Middle East conflict, which has pushed euro area inflation toward 3.3% and is now projected to average 3.0% for 2026.

Is this the ECB’s first rate hike this year?

No. This is the second time in 2026 that the ECB has raised its key interest rates to bring inflation back toward its 2% target.

How does this compare with the Federal Reserve?

The Federal Reserve has signaled it may raise US rates for the first time since 2023, pointing to similar inflation pressure from the same regional conflict.

When is the Bank of England’s next rate decision?

The Bank of England’s Monetary Policy Committee is scheduled to announce its next rate decision on September 17, 2026, a day after the ECB’s new rate took effect.

Related coverage on Tamara News

Sources

Six of Every Ten Export Dollars Korea Earned in August Were Tech

If you want to know whether the AI buildout is real, look at what leaves Busan. Record
South Korea chip exports helped push the country’s technology shipments to $59.98 billion in
August 2026. The figure comes from a joint report by the Ministry of Science and ICT and the Ministry of
Trade, Industry and Energy, released on 14 September. Information and communications technology passed 60
per cent of total exports for the first time.

What South Korea chip exports actually recorded

Semiconductors did most of the work. Chip shipments rose 209 per cent year on year to $46.67 billion.
Computers and communications equipment climbed 383.1 per cent to $6.4 billion.

Total ICT exports of $59.98 billion compare with $22.84 billion in August 2025, a rise of 162.6 per cent.
The sector posted a trade surplus of $41.37 billion, also a record.

Those growth rates are extraordinary by any normal reading of trade data. They come from the ministries’
own release, and they reflect both volume and price. High-bandwidth memory used in AI accelerators carries a
far higher unit value than the commodity memory that dominated earlier cycles.

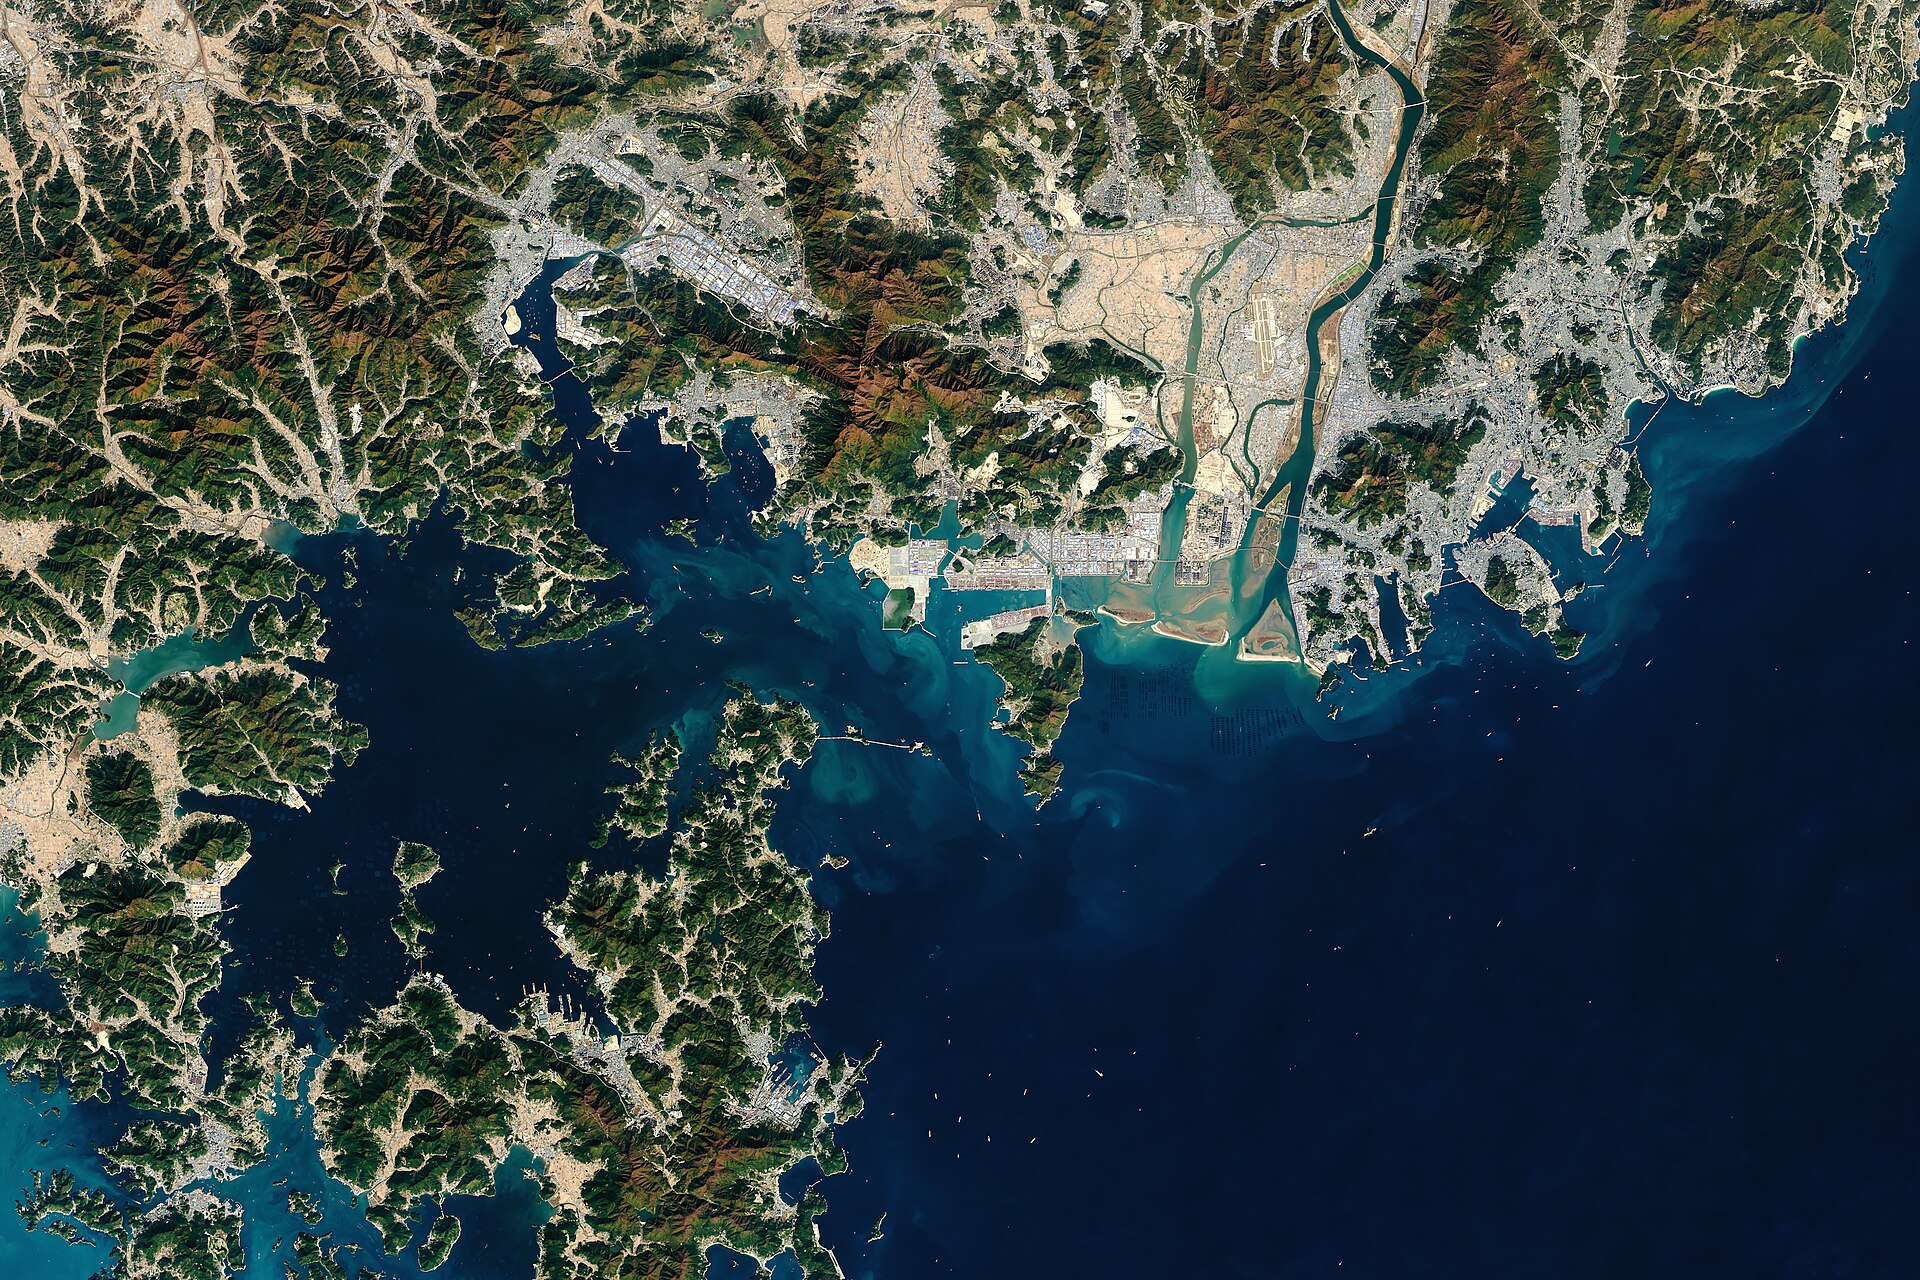
Satellite view of Busan container port, the gateway for South Korea chip exports
Busan container port from orbit. Korean memory and logic chips move through terminals like this one.

Why Korea is the cleanest read on AI demand

Samsung Electronics and SK hynix supply much of the world’s advanced memory, including the high-bandwidth
memory that AI accelerators require. Without it, a GPU cannot be assembled into a working system.

That gives Korean customs data an unusual property. It measures hardware actually shipped, not hardware
announced. Capital-expenditure plans can be revised quietly. Export tonnage cannot.

Demand spread widely by destination. Shipments to the United States rose more than 300 per cent.
Exports to China and Hong Kong, Vietnam, the European Union and India all rose sharply as well.

The breadth is the useful signal. A surge to one destination can mean a single customer stockpiling.
Growth across the United States, China, Vietnam, Europe and India at once points to broad build-out rather
than one buyer’s inventory decision.

Vietnam deserves a note of its own. Much of what ships there goes for assembly and test before moving on
again. Its numbers partly measure the same demand a second time, further along the chain.

The concentration underneath the record

A sector at more than 60 per cent of national exports is a strength and an exposure at the same time.
Reporting on the release noted that stripping ICT out would leave the country running a trade deficit of
about $6.6 billion for the month.

That is the risk in one number. Korea’s external accounts now depend heavily on one demand cycle in one
industry.

The timing sharpens it. These figures landed the same week AI lab chiefs called publicly for slower
frontier-model development, and chip stocks fell across three continents. Our reports on
that slowdown call and
on the Qualcomm-Amazon AI chip
deal
cover the demand side of the same market. Korea’s own policy response runs through skilled
migration too, as our piece on
China’s competing
computing plan
shows for the region.

What the record changes for the rest of the market

For buyers, sustained Korean output eases the memory shortage that has constrained accelerator supply.
For competitors, it raises the bar: matching this volume takes fabs that take years to build.

For policymakers elsewhere, the data is an argument in ongoing subsidy debates. Countries funding
domestic semiconductor capacity will cite these figures in both directions — as proof the market is worth
entering, and as proof of how far ahead the incumbents already are.

Whether the numbers hold

Three things decide that. The first is whether AI capital spending continues at its current pace into
2027. The second is memory pricing, which has driven much of the value growth and can fall quickly. The
third is export-control policy, which shapes where Korean fabs can sell and what equipment they can buy.

September data, due in mid-October, is the next check. A single record month proves a peak. Two
consecutive ones start to prove a trend.

Export data questions

How large were the exports?

ICT exports reached $59.98 billion in August 2026, up 162.6 per cent from $22.84 billion a year earlier.

How much of that was semiconductors?

Chip exports were $46.67 billion, a rise of 209 per cent year on year.

Who published the figures?

The Ministry of Science and ICT with the Ministry of Trade, Industry and Energy, in a report released on 14 September 2026.

What share of total exports is ICT now?

More than 60 per cent, the first time the sector has passed that threshold.

Why do these figures matter for AI?

Samsung and SK hynix supply much of the high-bandwidth memory AI accelerators need, so Korean shipments track real hardware demand.

What is the risk in the record?

Concentration. Reporting on the release noted that without ICT, Korea would have run a monthly trade deficit of about $6.6 billion.

Citations

Banks Lent SoftBank More Than It Asked For. Shareholders Disagreed

SoftBank borrowed more than it asked for, on the same day its shares had their worst session
since July. The SoftBank OpenAI loan came in at $11.87 billion, a two-year facility from
about 20 banks, against an original $10 billion target. Bloomberg reported the terms on 14 September 2026,
citing people familiar with the arrangement. The gap between what lenders would fund and what equity
investors would tolerate is the story.

What the SoftBank OpenAI loan consists of

The facility runs for two years. Around 20 banks committed to it, and the book closed above the target
rather than below it. Oversubscription of that size signals confidence among lenders.

It joins an existing stack. SoftBank already holds a $10 billion margin loan secured against its OpenAI
shares, with Goldman Sachs and JPMorgan among the lenders. Bankers have also discussed a bond sale of up to
$20 billion.

The company said last week it would repay the remaining $25.9 billion of a $40 billion bridge loan on 15
September. Taken together, SoftBank has committed roughly $65 billion to OpenAI by October, for a stake
reported at around 13 per cent.

Tokyo Stock Exchange trading floor where the SoftBank OpenAI loan moved the shares
The Tokyo Stock Exchange. SoftBank shares fell as much as 13 per cent on the day the facility was reported.

Why the shares fell while the banks said yes

SoftBank stock dropped as much as 13 per cent on Monday, its steepest fall since 17 July. The trigger was
not the loan itself.

Leading AI executives spent the weekend arguing publicly for a slower pace of frontier-model development.
Markets read that as a demand signal and repriced the AI hardware and infrastructure complex. SoftBank, as
the most visible listed proxy for OpenAI exposure, took a heavier hit than most.

So two verdicts arrived on the same day. Credit markets funded the position above target. Equity markets
marked it down. We covered the underlying argument in our report on
the AI slowdown call from
Amodei, Altman and Musk
.

The leverage question the SoftBank OpenAI loan raises

Borrowing against a private stake works while the stake’s value holds. It compounds against you when the
value falls, because collateral requirements do not wait for a recovery.

Timing adds to the pressure. Sam Altman told Fortune that OpenAI will not proceed with a public offering
this year while it addresses safety concerns. An IPO is the cleanest route to liquidity for a stake of this
size. Pushing it out extends the period during which SoftBank services debt without a market price to
refinance against.

None of that makes the position unsound. It does mean SoftBank’s cost of capital becomes a variable worth
watching for anyone in the OpenAI orbit — follow-on rounds, secondary sales and listing timelines all move
with it.

There is precedent for both outcomes. SoftBank’s concentrated bets have produced its best returns and its
worst. The Alibaba stake funded two decades of expansion. The Vision Fund’s later vintages did not. A single
position this large works exactly as well as the underlying asset does.

What differs this time is the funding mix. Earlier bets leaned on fund structures with outside limited
partners sharing the downside. This one leans on debt secured against the asset itself, which keeps more of
the upside and all of the risk on SoftBank’s own balance sheet.

What it says about the AI funding cycle

Private credit is still flowing into AI infrastructure at scale. Our reports on
Positron AI’s $875 million
round
and Google’s
Finnish data-centre investment
show the same pattern in different corners of the stack.

What has changed is the divergence. Lenders and public shareholders are now pricing the same assets
differently, and they are doing it in the same week. That gap tends not to persist. One side usually moves
toward the other.

What to watch on SoftBank’s balance sheet

Three markers will show which way it resolves. First, whether the $20 billion bond sale proceeds, and at
what spread. Second, whether the margin loan against the OpenAI stake gets topped up or repriced. Third,
whether the October funding target of roughly $65 billion is met in full.

Also watch OpenAI’s own signals on timing. Any change to the listing schedule feeds straight back into
SoftBank’s refinancing options.

Questions on the financing

How large is the loan?

$11.87 billion, arranged as a two-year facility from about 20 banks, above an initial $10 billion target.

Who reported it?

Bloomberg and The Japan Times reported the terms on 14 September 2026, citing people familiar with the matter.

How much has SoftBank committed to OpenAI?

Roughly $65 billion by October, for a stake reported at around 13 per cent.

Why did the shares fall?

AI executives called publicly for slower frontier development over the weekend, and markets repriced AI-linked stocks. SoftBank fell as much as 13 per cent.

Is OpenAI planning to list this year?

Sam Altman said it would not proceed with a public offering this year while the company addresses safety concerns.

Primary sources

Cox Spectrum Rebrand Reaches Customers in Mid-September

The Cox Spectrum rebrand arrives in customers’ homes this month. Charter Communications completed its acquisition of Cox Communications on 20 August 2026, alongside a separate merger with Liberty Broadband, in a transaction valued at $34.5bn. The paperwork closed in August; the part customers notice — Spectrum branding, Spectrum pricing and Spectrum packaging replacing Cox’s — begins rolling into former Cox markets from mid-September.

What closed in August

Charter described the combined business as the leading broadband and video company in the United States, serving 37 million customers across 45 states. That figure is the company’s own, published in its completion announcement, and it counts customer relationships rather than individual services.

Two transactions closed together: the Cox acquisition and a merger with Liberty Broadband, the holding vehicle that had a large stake in Charter. Collapsing that structure simplifies the ownership chain at the same time as the operating footprint expands. Charter also filed the relevant disclosure with the SEC; the 8-K exhibit is the primary document.

The part customers see this month

For households in former Cox territories — Las Vegas, Phoenix, San Diego, Hampton Roads, Omaha, New Orleans and others — the change is a rebrand plus a repricing. Charter is moving its Spectrum products, pricing and packaging into those markets, which means the shape of the bill changes even where the underlying connection does not.

Charter has also said it will give former Cox internet customers who are not already on Cox Mobile a free year of mobile service. That is a company promotion with the usual purpose: convert broadband-only households into bundled ones, which are materially harder to churn. Treat it as a customer-acquisition offer rather than a windfall, and read the terms for what happens in month thirteen.

What does not change immediately: the physical network. The cable plant, the node splits and the fibre in the ground are the same assets they were in July. Service quality in a given neighbourhood is a function of that plant, not of the logo on the router.

The naming arrangement, which is genuinely odd

Within a year of closing, the parent company is due to take the Cox Communications name while continuing to operate its services under the Spectrum brand everywhere. So the acquirer adopts the target’s corporate identity and the target’s customers adopt the acquirer’s consumer brand. Variety covered the arrangement at closing.

The logic is family ownership. Cox is a long-held private family business, and preserving the name is the kind of term that gets negotiated into a deal of this size. For customers it is a distinction without a difference: the entity on the corporate filings will say Cox; the app, the bill and the truck will say Spectrum.

What a bigger cable company means for prices

Cable consolidation in the US has generally been approved on the argument that cable operators no longer compete against each other — their footprints do not overlap — so combining them does not reduce choice in any given street. That argument is technically sound and practically incomplete. Scale changes negotiating power with programmers, purchasing power for equipment, and the operator’s ability to fund fibre upgrades and mobile subsidies.

The competitive pressure that actually disciplines prices for most US households now comes from elsewhere: fibre overbuilders and fixed-wireless broadband sold by mobile carriers, which has taken meaningful share from cable over the past few years. A larger Charter is better placed to respond to that pressure — the free-mobile offer is exactly such a response — but it does not remove it.

What to watch: whether Spectrum pricing in former Cox markets lands above or below what those customers were paying, and how quickly promotional rates step up. Those two numbers will tell the story better than any merger statement.

Customer questions

Is Cox now Spectrum?

Yes for consumer-facing purposes. Charter completed the acquisition on 20 August 2026 and is rolling Spectrum branding, pricing and packaging into former Cox markets from mid-September.

How big was the deal?

$34.5bn, completed alongside a separate merger with Liberty Broadband.

How many customers does the combined company have?

Charter says 37 million customers across 45 states. That is the company’s own figure.

Will my equipment or connection change?

The physical network does not change with a rebrand. Equipment swaps happen over time as Spectrum standardises hardware, but the cable plant serving an address is the same.

What is the free mobile offer?

Charter has said former Cox internet customers not already subscribing to Cox Mobile are eligible for a free year of mobile service. It is a promotional offer; check the terms for what applies after twelve months.

Why will the parent company be called Cox?

Under the deal terms the parent adopts the Cox Communications name within a year while services continue to operate as Spectrum.

Continue with these