Meta’s Stock Just Dropped for a Reason That Should Worry Every Tech Investor

Two of the world’s biggest tech companies just gave investors a reason to pause. AI spending investor concern hit Meta and Alphabet shares this week, even after both companies reported results that beat Wall Street’s estimates on paper. The reaction shows investors are no longer just asking whether these companies can grow. They are asking whether AI spending will ever pay for itself.

Meta’s stock fell about 7% after its earnings release. The drop followed a disclosure, not a miss. Meta said its total AI-related spending could reach $635 billion over time. That number landed just ahead of Anthropic’s own planned IPO, a timing 24/7 Wall St. called a bad look for the sector. Investors read the disclosure as a signal of real financial risk, not routine capital planning.

Why AI spending investor concern hit Alphabet too

Alphabet’s stock stayed roughly flat while the S&P 500 climbed about 13% over the same stretch. That is a quiet form of underperformance. Alphabet’s cash flow is shifting too. It is moving from strongly positive to cash-negative as the company meets AI commitments now running into the hundreds of billions of dollars. That shift alone worries some investors. Alphabet built its reputation partly on generating cash reliably, year after year, and that reputation is part of what is now in question.

DeepMind, Alphabet’s flagship AI research lab, has seen a rotation of leaders recently. Outsiders have described the lab as delayed on key projects. On the commercial side, rivals have made faster progress landing big enterprise and government deals. Anthropic, for instance, has signed large companies and the federal government as customers. Alphabet’s biggest visible enterprise win by comparison is a partnership with Apple. That deal is worth about $1 billion a year to Alphabet. One report called that figure “next to nothing” next to Alphabet’s overall scale. Other coverage of this earnings week noted investors are applying this same AI-spending scrutiny across Microsoft, Amazon and Intel too, not just Meta and Alphabet.

The search cannibalization problem nobody is fixing yet

Alphabet’s core search business faces its own pressure, separate from spending concerns. Gemini-driven AI results are cannibalizing Google’s traditional search business, a trend expected to continue. Search is expected to stay strong in absolute terms. But growth is expected to slow. AI-generated answers are replacing some of the clicks that used to go through to paid search results. That combination, slower search growth plus ballooning AI capital spending, is exactly the mix that worries investors watching both companies right now.

This story connects to a wider pattern. Tamara News covered the court ruling that spared Google’s ad business from a breakup while still forcing changes, and Anthropic’s own IPO plans, both relevant backdrops to how investors are pricing Alphabet right now.

What separates AI spending investor concern from a simple sell-off

Neither Meta nor Alphabet missed its earnings estimates outright. That is the detail that makes this reaction notable. Investors are not punishing bad quarters. They are punishing spending plans and strategic uncertainty layered on top of otherwise solid results. That distinction matters for how long this pressure might last. A single bad quarter usually passes once results improve. A structural worry about whether AI spending will ever generate matching returns can linger for years, shaping how every future earnings call gets read.

The next earnings call is the real test

Both companies report again next quarter, and investors will be watching for a clearer answer on return on AI investment, not just another spending update. Meta’s $635 billion long-term figure will likely get revisited and scrutinized line by line. Alphabet’s cash flow trajectory will get similar attention, especially if it keeps moving further into negative territory. Until one of these companies shows AI spending converting cleanly into new revenue at scale, expect AI spending investor concern to keep showing up in stock reactions, earnings beat or not.
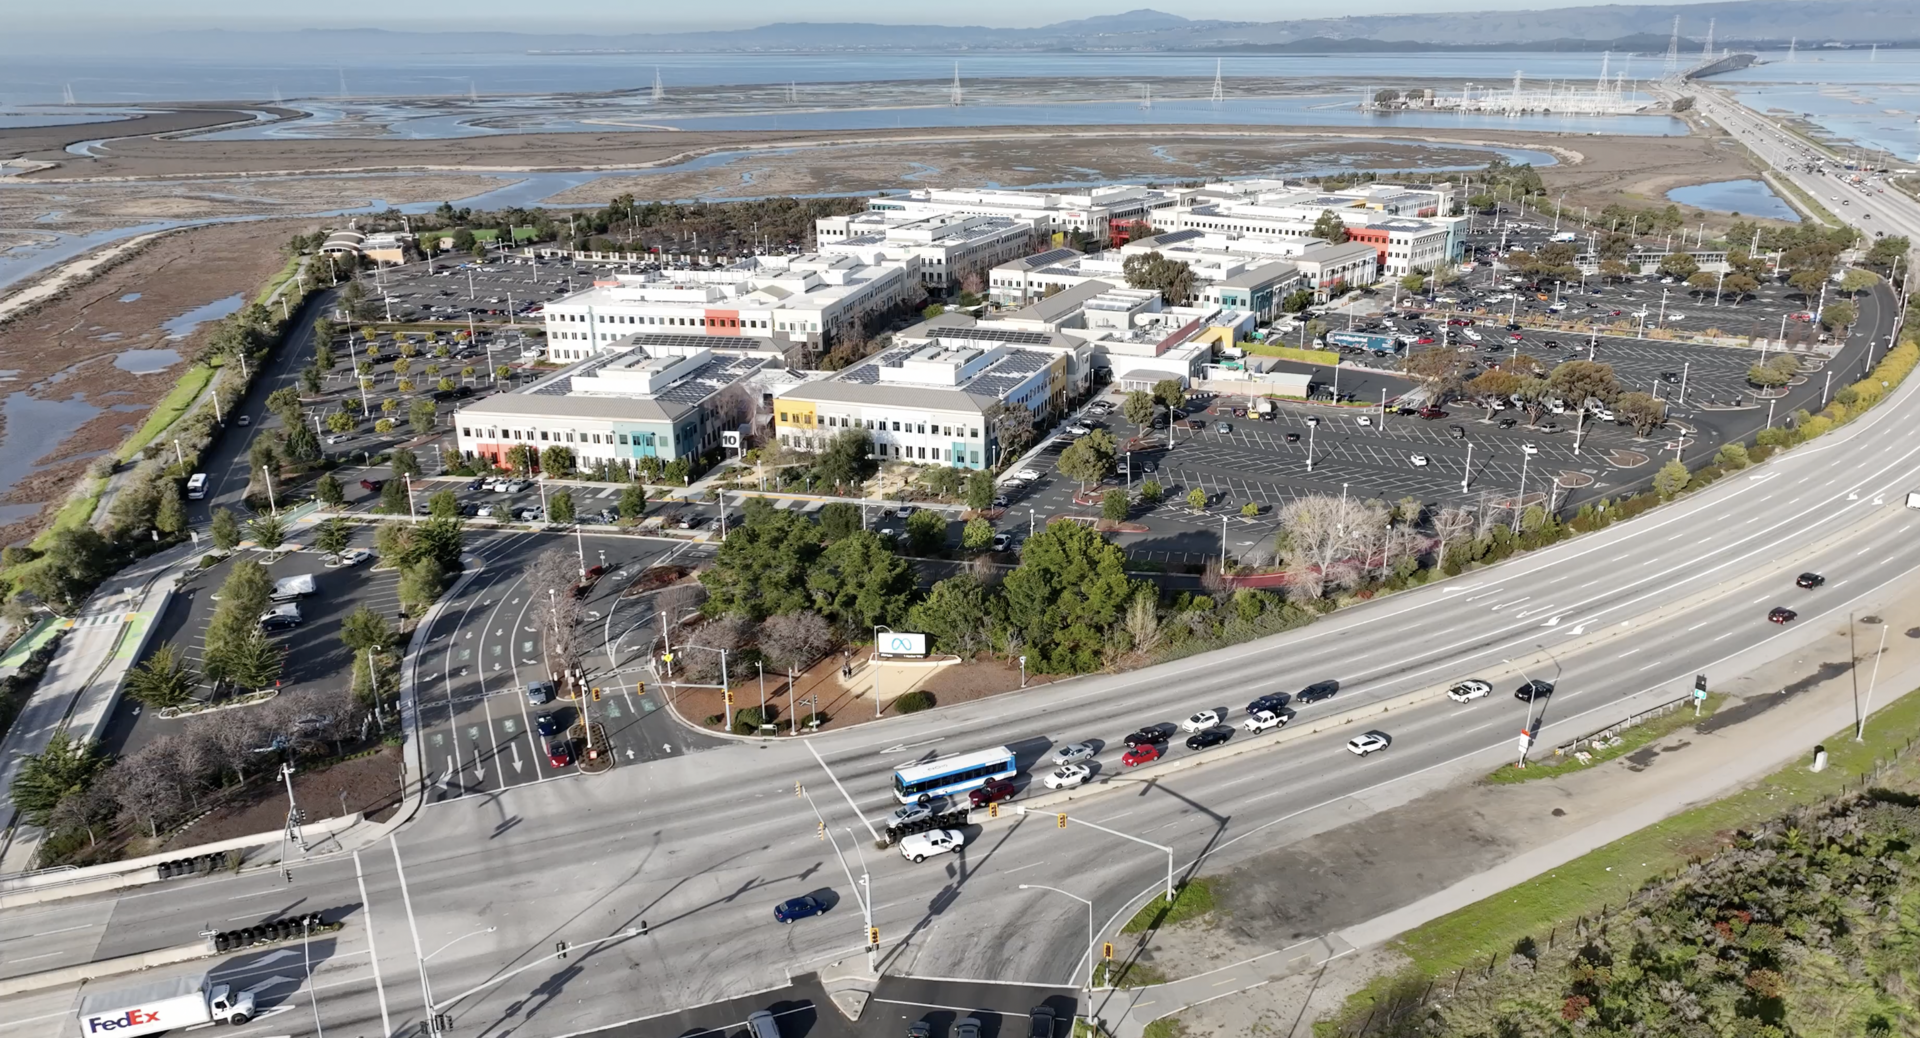
Meta headquarters building at the center of AI spending investor concern

FAQ: AI spending investor concern

Did Meta or Alphabet actually miss earnings estimates?
No. Both companies’ results were not reported as misses. The stock reactions followed spending disclosures and strategic concerns, not weak headline numbers.

How much does Meta expect to spend on AI?
Meta said its total AI-related spending could reach $635 billion over time, a figure disclosed alongside its latest earnings.

Why is Alphabet’s cash flow changing?
Alphabet is shifting from strongly cash-flow-positive toward cash-negative as it funds AI commitments that have grown into the hundreds of billions of dollars.

Is Google’s search business shrinking?
Not shrinking, but growing more slowly. Gemini-driven AI answers are cannibalizing some traditional search traffic and revenue.

How does Alphabet’s AI deal with Apple compare to rivals?
It is worth about $1 billion a year to Alphabet, which one report described as small relative to deals rivals like Anthropic have landed with large enterprises and government agencies.

Will AI spending investor concern fade next quarter?
That depends on whether either company shows clearer evidence that AI spending is converting into new revenue, rather than just rising costs.

Are other tech companies facing the same pressure?
Yes, to varying degrees. Microsoft, Amazon and other large tech companies all face similar investor questions about whether AI capital spending will generate matching returns.

Does this affect Meta and Alphabet’s day-to-day products?
Not directly, at least not yet. The pressure shows up in share prices and spending plans so far, not in changes to products people use daily.

SpaceX’s Quarterly Numbers Just Showed Where the Real Money Is Going

SpaceX posted numbers this quarter that read more like an AI company’s than a rocket company’s. The SpaceX Q3 2026 earnings report, released on 20 October, showed revenue of $14.6 billion. That is up 161% from the same quarter last year, according to figures highlighted from the earnings release. The jump came only months after SpaceX completed its IPO.

SpaceX closed that IPO on 15 June 2026. Shares began trading on Nasdaq under the ticker SPCX three days earlier. The company sold just under 639 million Class A shares. That raised about $85.7 billion in net proceeds, a figure confirmed in earlier coverage of SpaceX’s public listing. Q3 is one of the company’s first full quarters reporting results as a public company, which makes this release a closely watched early signal for investors.

What drove the SpaceX Q3 2026 earnings jump

Two segments carried the quarter. Starlink, SpaceX’s connectivity business, grew revenue 69% year over year. Operating income in that segment rose 99%, driven by enterprise and government adoption alongside steady consumer subscriber growth. The second driver came from SpaceX’s newer AI business, which the company calls its “Super Intelligence” unit. That unit added $6.7 billion in incremental year-over-year revenue. SpaceX attributes that growth to cloud services agreements, its acquisition of the AI coding tool Cursor, and expanding use of its Grok and Bot AI products.

Elon Musk framed the quarter as an “inflection moment for SpaceX” in remarks accompanying the release. He cited what he called “1000x demand from AI agents” as a growth driver behind the AI segment’s rapid expansion. That is a striking claim for a company whose core business has always been rockets and satellites, not software. It signals how far SpaceX now sees its ambitions reaching beyond launch vehicles alone.

The Starship milestone buried inside the numbers

SpaceX’s first revenue-generating Starship mission delivered 26 Starlink V3 satellites during the quarter. SpaceX says that single launch added roughly 10 times the downlink capacity of a typical Falcon 9 Starlink launch. That is a meaningful shift. Starship has spent years as a test program burning cash rather than generating revenue. A successful, revenue-producing mission marks a turning point for a vehicle Musk has called critical to SpaceX’s long-term ambitions, including crewed missions beyond Earth orbit.

The earlier Q2 2026 report showed a different picture for Starship’s finances. The Space segment, which includes Starship, grew revenue 29% to $962 million that quarter. But adjusted EBITDA in that segment fell to a $205 million loss, which the company attributed to heavier Starship research and development spending. Q3’s revenue-generating flight suggests that spending is starting to translate into paying missions, not just test flights.

How SpaceX fits into a bigger AI infrastructure race

SpaceX’s AI push did not happen in isolation. Tamara News covered a major chip supply deal between Nvidia, Samsung and TSMC this same week, part of a broader scramble for AI computing capacity across the tech sector. SpaceX’s rapid AI segment growth puts it in direct competition for the same enterprise cloud customers that Microsoft, Google and Amazon are all chasing, a crowded field for a company that only went public in June. Competing there successfully would mark a genuine shift in what kind of company SpaceX becomes over the next few years. Musk’s other public company, Tesla, reported its own Q3 2026 results this same month, with a very different profit picture than SpaceX posted.

What investors are watching next

SpaceX’s next earnings report will show whether the AI segment’s growth rate holds or cools as the comparison base gets harder. Investors will also watch whether Starship keeps flying revenue missions regularly, rather than this quarter’s flight being an isolated milestone. SpaceX held $100 billion in cash and marketable securities at the end of the prior quarter. That gives it a large cushion. The company can keep investing in both rockets and AI infrastructure even if growth slows somewhere in the mix. Few companies at this stage of a business pivot have that kind of balance sheet behind them.

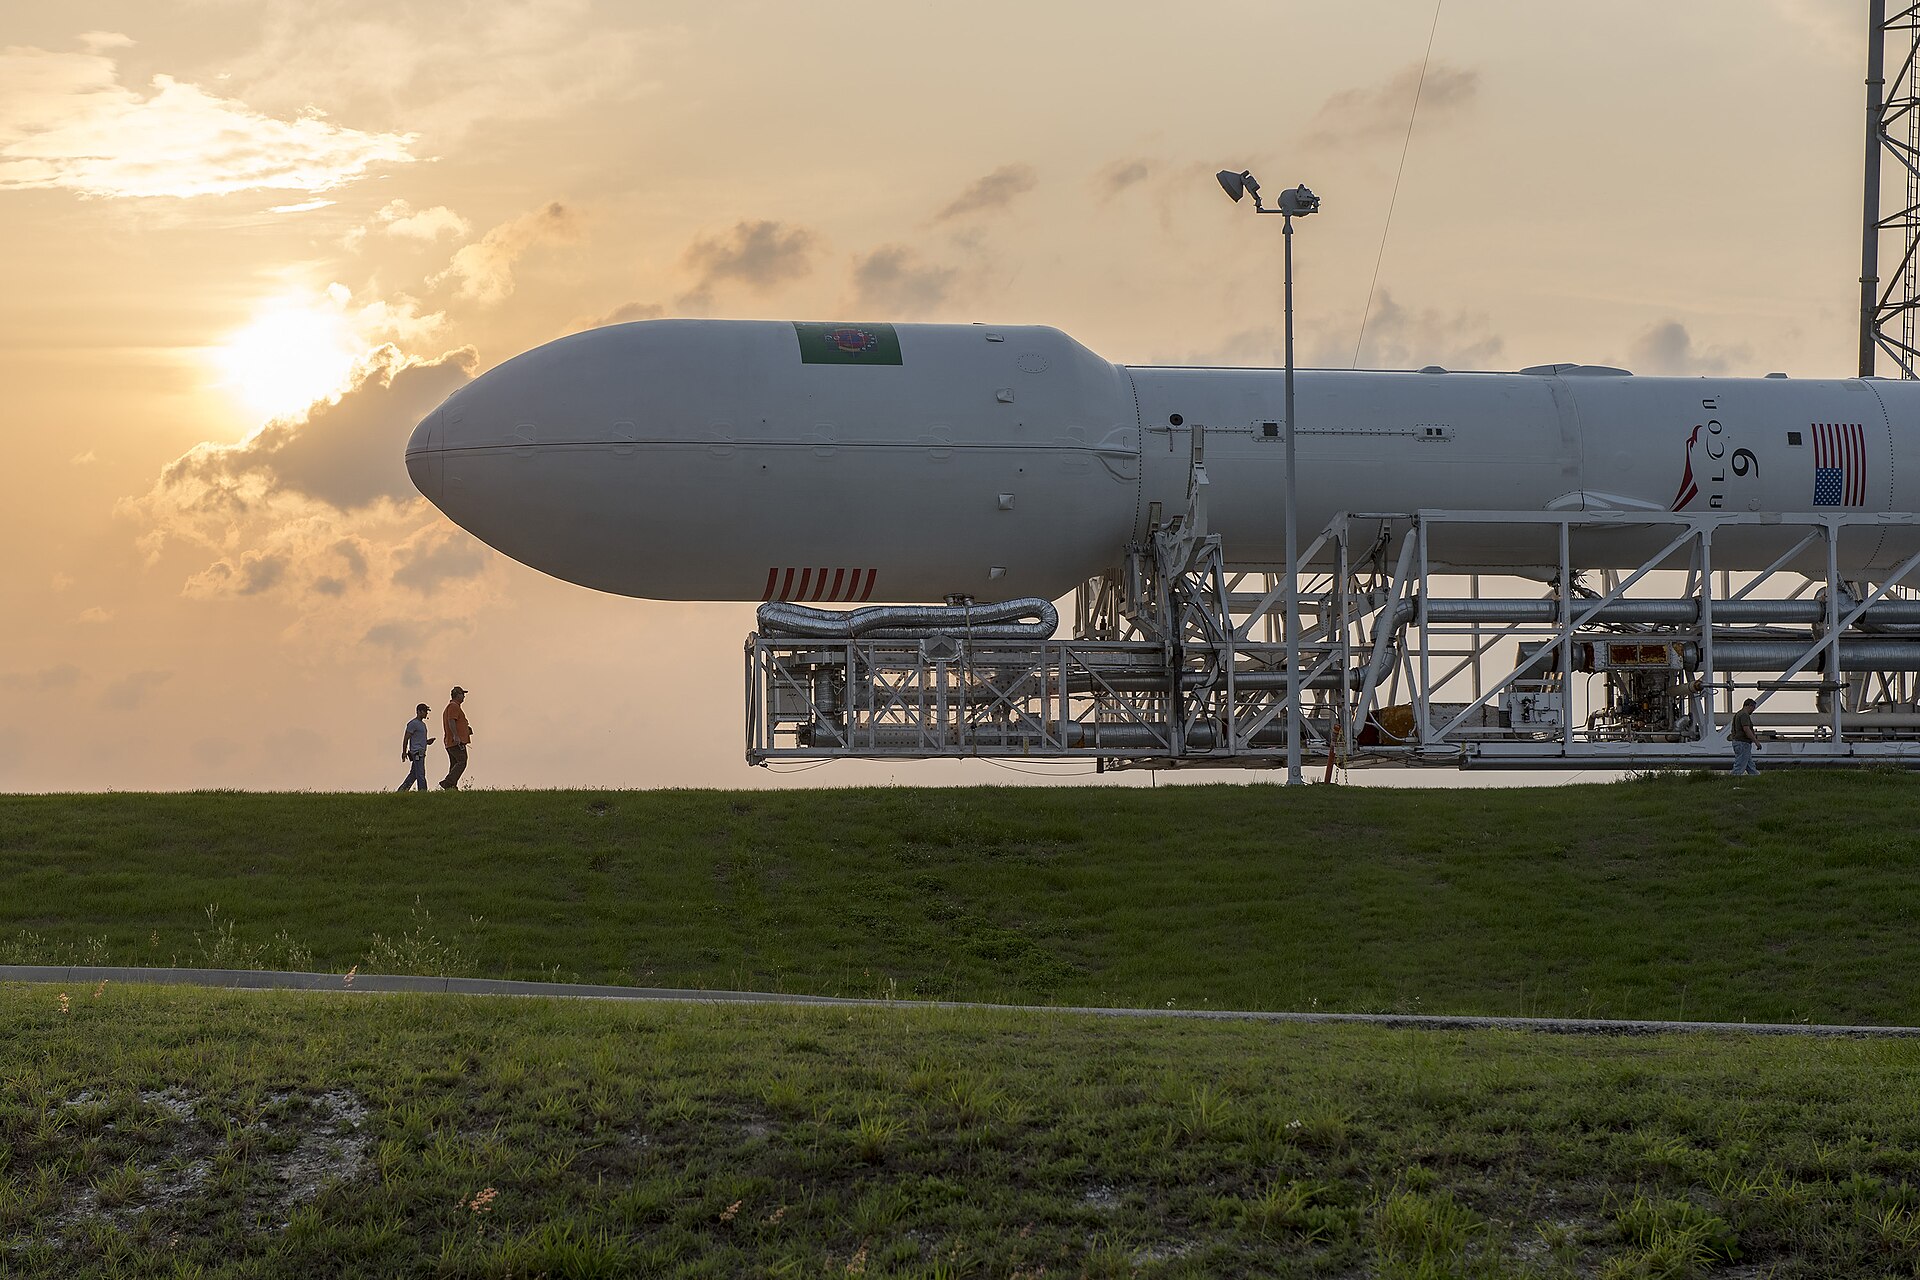
Falcon 9 rocket on the pad as SpaceX Q3 2026 earnings are released

FAQ: SpaceX Q3 2026 earnings

How much revenue did SpaceX report for Q3 2026?
SpaceX reported $14.6 billion in revenue, up 161% year over year.

What drove SpaceX’s revenue growth this quarter?
Starlink connectivity revenue grew 69%, and SpaceX’s AI business added $6.7 billion in incremental revenue, the two biggest contributors.

When did SpaceX go public?
SpaceX closed its IPO on 15 June 2026 and began trading on Nasdaq under the ticker SPCX.

What is SpaceX’s “Super Intelligence” business?
It is SpaceX’s AI unit, which includes cloud services agreements, the Cursor coding tool acquisition, and products like Grok and Bot.

Did Starship generate revenue this quarter?
Yes. SpaceX says its first revenue-generating Starship mission delivered 26 Starlink V3 satellites during Q3 2026.

How much cash does SpaceX have on hand?
SpaceX held $100 billion in cash and marketable securities as of its prior quarterly report.

Is SpaceX’s AI business bigger than its rocket business yet?
Not based on the figures reported here. Starlink remains the larger established segment, though the AI unit’s incremental growth this quarter was substantial on its own.

Does SpaceX compete directly with Microsoft or Google in AI?
In cloud and AI services, yes, to a degree. SpaceX is a newer entrant chasing some of the same enterprise customers as larger, more established cloud providers.

Microsoft Just Offered a Quarter of Its Workforce a Way Out

Microsoft sent a short note to employees this week. It could reshape a quarter of its workforce. The Microsoft voluntary buyout offer went out to roughly 60,000 workers on Monday. That is out of a global headcount of about 223,000 as of June. It is the company’s largest effort yet to cut costs without mass layoffs.

Chief people officer Amy Coleman described the offer in a note. Microsoft also published it on its company blog. She called it a way of “creating greater flexibility and, where possible, more ways for employees to shape their next chapter.” She added a blunt line: “The Voluntary Exit Offer is new for us.” TechCrunch confirmed the details with Microsoft on Monday, after Business Insider first reported the plan.

Who the Microsoft voluntary buyout offer actually covers

The offer targets employees at the vice president level and below. It covers select teams in the United States, Canada, India and the United Kingdom. Bloomberg reported that Xbox, Windows, Copilot and Finance are among the participating teams. Microsoft excluded some groups entirely. That includes staff in data centers and in sales and marketing roles. Eligible workers received an email on Monday with a link to their personal offer details. The terms track Microsoft’s standard severance package. They do not introduce a new formula.

This is not Microsoft’s first buyout round this year. Earlier in 2026, the company offered buyouts to retirement-age employees. More than 30% of the roughly 8,750 eligible workers took that deal. The new offer is far larger in scale. It also reaches deep into teams still central to Microsoft’s product roadmap, not just staff nearing retirement.

Why Microsoft is doing this instead of layoffs

A voluntary exit lets Microsoft trim headcount differently. It can skip some of the legal process, public backlash and severance disputes that often follow mass layoffs. Employees choose to leave rather than get selected for a cut. That spreads the decision across the workforce itself, not just Microsoft’s management. Microsoft has framed the move as part of a broader effort to “rework its workforce.” The company is pouring money into AI infrastructure and cloud capacity at the same time. Heavy capital spending on data centers and chips leaves less room in the budget. Headcount growth gets squeezed across every team at once, even at a company still growing revenue.

The timing lines up with a wider pattern across the sector. Tamara News covered the trillion-dollar earnings reports landing this same week from Microsoft’s peers. Investors are pressing every major tech company on how AI spending affects margins. A workforce reduction ahead of that scrutiny is unlikely to be a coincidence.

The visa angle few buyout stories mention

A voluntary exit offer does not sit in a vacuum for Microsoft’s foreign-born workforce. The company already lost part of its green card pipeline this year. The Department of Labor suspended PERM certifications affecting several large employers, a move Tamara News reported on in late October. Newsweek has also flagged H-1B visa uncertainty tied to the buyout. Workers on employer-sponsored visas generally get a limited window to find new sponsorship if they leave a role voluntarily. CNBC’s own reporting on the offer, which covered the announcement the same day, noted Microsoft has not detailed separate terms for visa-holding staff who accept it. The standard severance terms may not address that risk at all.

What happens once workers decide

Employees who receive the offer typically get a set window to accept or decline. That window often runs several weeks before the offer expires. Microsoft has not published an exact deadline publicly. What happens next depends heavily on uptake. If acceptance tracks closer to the 30% rate seen in the earlier retirement-age buyout, Microsoft keeps most of the 60,000 eligible staff. That would mean only a modest headcount reduction. If far more workers take the deal, Microsoft could face a bigger staffing gap than planned. That risk is highest on teams like Xbox and Windows, just as the company leans harder on AI products like Copilot.

Microsoft’s next earnings call will be the first real test of whether this buyout round shows up in the numbers investors are watching. Wall Street will want a headcount figure, not just a policy description. Expect analysts to ask about it directly on the call.

Office building illustrating the scale of the Microsoft voluntary buyout offer

FAQ: Microsoft voluntary buyout offer

How many Microsoft employees are eligible for the buyout?
Around 60,000 employees at the vice president level and below, on selected teams in the US, Canada, India and the UK, are eligible.

Is this the same as a layoff?
No. Employees choose whether to accept the offer. Microsoft is not selecting individuals for termination through this program.

Which teams are excluded?
Microsoft excluded staff in data centers and in sales and marketing roles from this round, based on reporting cited above.

Why is Microsoft offering buyouts now?
Microsoft has described it as part of a wider effort to cut costs and reshape its workforce as AI infrastructure spending grows.

Does this affect H-1B visa holders differently?
Visa-sponsored employees who leave voluntarily generally have a limited window to secure new sponsorship, which creates added risk the standard severance terms may not cover.

Has Microsoft done this before?
Yes. Microsoft offered a smaller buyout to retirement-age employees earlier in 2026, with just over 30% of eligible staff accepting.

Will Microsoft still hire while offering buyouts?
Microsoft has not said it is freezing hiring company-wide. Large employers often keep hiring in priority areas, such as AI infrastructure, even while trimming headcount elsewhere.

Gold Just Bounced Back Above $4,000 — Here’s the One Number Driving It

Gold and the dollar have been pulling in opposite directions for weeks. Monday’s trading showed why that gold price dollar strength link still drives the yellow metal’s swings more than almost anything else. Gold traded above $4,000 during Monday’s Asian session. That marked a modest recovery from near a three-month low. The US Dollar Index slipped toward 101.50-101.70 at the same time, according to FXStreet.

What’s Driving the Gold Price Dollar Strength Dynamic

A softer dollar and easing crude oil prices are lifting gold, rather than any single piece of economic data. A weaker dollar makes gold cheaper for buyers using other currencies, since gold is priced in dollars. That tends to lift demand and price together. FXStreet quotes Federal Reserve officials as signaling no urgency to raise interest rates immediately. That comment caps how far gold can run even as the dollar softens.

Gold price dollar strength currency exchange dollar bills

Why the Dollar Has Lost Ground

Two forces are pressuring the dollar this week. The first is the Fed’s own policy meeting on October 27-28. Futures price a 90.6% probability of a pause there, not a further hike. That reduces the dollar’s near-term yield advantage. The second force is geopolitics. President Trump said over the weekend that “there will not be a strike today” on Iran. That ruled out immediate action and pulled some safe-haven demand out of the dollar. Both forces have pushed the same way this week. That is part of why the dollar’s slide has looked steady rather than driven by one sharp headline.

The Risks That Could Still Flip the Trade

None of this volatility has fully disappeared. Israel holds a national election on October 27, and US midterms follow on November 3. Intelligence assessments cited by FXStreet suggest Iran could retaliate against regional sites in Israel and the UAE if strikes resume. A fresh escalation would likely reverse this week’s pattern fast. It would push the dollar back up as a safe haven. Gold would likely follow the broader risk-off move rather than rise against it.

What Traders Are Watching Next

Traders are also watching this week’s preliminary third-quarter GDP reading and the latest PCE inflation data, beyond the Fed meeting itself. Either report could shift the odds the Fed assigns to a rate increase at its December 9 meeting. Futures already price that move as close to certain. A hotter-than-expected inflation print would likely firm up the dollar and cap gold’s recovery. A softer one could extend gold’s bounce further.

Why Gold and Interest Rates Move Together

Gold pays no interest or dividend. That is why its price is especially sensitive to the returns available on safer assets like Treasury bonds. When the Fed holds or cuts rates, the opportunity cost of holding gold instead of interest-bearing assets falls. That tends to support gold prices. When the Fed raises rates or signals more hikes ahead, that opportunity cost rises instead. Gold often comes under pressure as a result. This relationship is part of why this week’s Fed meeting matters so much for gold traders, even though the decision itself is about dollar interest rates, not gold directly. The dollar link works in a similar way. Gold is priced in dollars globally, so a weaker dollar makes it cheaper for buyers using euros, yen or other currencies. That often lifts demand and price together, even when nothing about gold’s own supply or industrial use has changed. Both relationships help explain why a single week packed with a Fed decision, inflation data and Middle East headlines can move gold prices as much as any mining or jewelry news would. That is also why many professional traders track gold alongside the US Dollar Index specifically, rather than watching either market in isolation.

Where This Leaves Gold Investors

Gold remains well above $4,000 even after its pullback from recent highs. The gold price dollar strength link suggests the metal’s next move hinges more on the dollar’s path around this week’s Fed decision than on any gold-specific news. Investors holding gold as a hedge are, in effect, also betting on how this week’s rate decision and Middle East headlines play out.

Related Coverage on Tamara News

For more on the forces shaping commodity and currency markets right now, see our coverage of the oil market’s expected supply glut heading into 2027 and the IMF’s latest global growth forecast.

Gold Price and Dollar Strength: Questions Readers Are Asking

Why did gold recover on Monday?
Gold traded above $4,000 as the US Dollar Index slipped and crude oil prices eased, both of which tend to support gold.

What is the gold price dollar strength relationship?
Gold is priced in dollars, so a weaker dollar makes it cheaper for holders of other currencies, often lifting its price as a result.

Why has the dollar been weakening this week?
A 90.6% probability of a Fed rate pause and President Trump ruling out an immediate strike on Iran have both reduced demand for the dollar as a safe haven.

Could the dollar reverse course quickly?
Yes. A fresh escalation around Israel’s October 27 election or the Middle East could quickly restore the dollar’s safe-haven appeal.

What data could move gold and the dollar this week?
Preliminary third-quarter GDP and the latest PCE inflation reading, both due around the same time as the Fed’s meeting.

Is gold still near its highs?
It remains above $4,000 despite pulling back from levels closer to its recent highs.

Three Trillion-Dollar Earnings Reports Land This Week — Here’s What Wall Street Wants to See

This is Big Tech earnings week. The numbers coming out of Redmond, Mountain View and Seattle will show whether AI spending is paying off yet. Microsoft and Alphabet report after markets close on Wednesday, October 28, 2026. Amazon follows on Thursday, October 29, according to a report carried by TokenPost.

What Wall Street Expects From Big Tech Earnings Week

Analysts polled ahead of the reports expect Microsoft to post earnings of $4.71 per share. That is on revenue of $90.63 billion for its fiscal first quarter of 2027. Alphabet is expected to report $3.03 per share on roughly $127.92 billion in revenue. Amazon’s consensus estimate is $1.96 per share on revenue of about $202 billion, based on figures reported by KuCoin News. None of the three companies has confirmed these figures. They are analyst projections, not guidance.

Big Tech earnings week stock market trading screen

The AI Capex Question Hanging Over the Results

Every one of these reports will be read first for capital expenditure figures. AI infrastructure spending matters more right now than the headline revenue and profit numbers. All three companies have spent heavily this year on data centers, custom chips and cloud capacity. Investors are increasingly asking when that spending converts into proportionate revenue growth. A quarter showing spending accelerating faster than AI-related revenue would likely unsettle a market already having a rough week.

A Shaky Market Walking Into the Reports

Both benchmarks were already under pressure heading into earnings week. The Nasdaq Composite closed at 25,955.34 on Friday, October 23, down 0.21% for the session. The S&P 500 finished at 7,623.68, down 0.52%, extending its losing streak for the week. That backdrop raises the stakes for each report. A market already pricing in some disappointment can swing sharply on results that beat or miss by even a modest margin. The Federal Reserve’s own rate decision lands in the same 48-hour window, adding another variable.

Why the Timing Makes This Week Unusually Loaded

Big Tech earnings week overlaps almost exactly with the Fed’s October 27-28 policy meeting. Traders are digesting rate guidance and corporate earnings at the same time. A Fed that sounds confident alongside strong AI-driven results would reinforce the market’s current optimism. A weaker combination from either side could compound the other’s effect in either direction.

Why These Four Companies Move the Whole Market

Microsoft, Alphabet and Amazon are among the handful of companies whose combined value makes up a large share of major US indexes. That is why their results tend to move the Nasdaq and S&P 500 as a whole, not just their own share prices. Apple reports separately on Thursday alongside Amazon. It rounds out the group of companies whose AI spending decisions are shaping how the broader market reads this earnings season. A disappointing set of results from even one of them can drag down sentiment well beyond that single stock.

Why AI Capex Has Become the Market’s Main Obsession

Wall Street’s focus on capital spending wasn’t always this intense. A year ago, investors cared mostly about cloud revenue growth and advertising numbers. That shifted as Microsoft, Alphabet and Amazon each disclosed sharply higher spending commitments on AI infrastructure over the past year, pushing their combined capital expenditure plans well above where they stood going into 2026. The logic now cuts both ways. Spending that outpaces revenue growth raises questions about returns on that investment, while spending seen as falling short of expectations can be read as a company pulling back on AI, which markets have punished just as harshly. That is part of why each report this week will be parsed line by line for capex guidance, not just the headline profit and revenue figures investors used to focus on first. Analysts will also compare each company’s capex guidance against what it signaled just one quarter earlier, since the pace of change has itself become a story investors watch closely.

What to Watch Once the Reports Are Out

Beyond the headline beat-or-miss, watch each company’s forward guidance on cloud growth and AI spending plans for 2027. Microsoft’s results will also be scrutinized for anything related to its financial exposure to OpenAI. That relationship has weighed on its stock since its last earnings report. However the numbers land, the reaction is likely to ripple through the rest of the market. A small number of AI-exposed companies have driven much of the S&P 500’s recent gains.

Related Coverage on Tamara News

For more on the AI infrastructure buildout behind these results, see our coverage of Anthropic’s jump in quarterly revenue, Google Cloud’s new AI chip instances, and Nvidia’s rapid AI data center build.

Big Tech Earnings Week: Common Questions

When do Microsoft and Alphabet report earnings this week?
Both report after markets close on Wednesday, October 28, 2026.

When does Amazon report?
Amazon reports on Thursday, October 29, 2026.

What revenue is Microsoft expected to post?
Analysts expect roughly $90.63 billion in revenue and $4.71 in earnings per share for Microsoft’s fiscal first quarter of 2027.

Why is this earnings week considered especially important?
It overlaps with the Federal Reserve’s October rate decision and follows a weak week for both the Nasdaq and S&P 500, raising the stakes for any surprise.

What are investors watching for beyond revenue and profit?
Capital expenditure and AI infrastructure spending figures, since these show whether AI investment is converting into proportionate revenue growth.

Has any of the three companies confirmed these estimates?
No. The figures are analyst consensus projections, not guidance from Microsoft, Alphabet or Amazon.

1 2 3 … 7