FinCEN Beneficial Ownership Rule: What Foreign Founders Must Know

FinCEN beneficial ownership reporting for companies formed in the United States is permanently over, but foreign companies that register to do business in a US state can still have to report. FinCEN issued its final rule on 11 August 2026, and it took effect on 14 August, according to Greenberg Traurig. For founders outside the US, the answer depends on where the company was formed.

At a glance

What the final rule does

According to BDO, the rule (RIN 1506-AB67) makes permanent the relief from beneficial ownership reporting for US companies under the Corporate Transparency Act. It adopts the interim final rule of 26 March 2025 without substantive changes. Greenberg Traurig adds that US companies and US persons are permanently exempt, that FinCEN will delete information previously reported about individuals it reasonably believes are US persons, and that US persons who applied for FinCEN IDs need not update their original information.

Who still reports

Foreign legal entities that registered to do business in a US state or Tribal jurisdiction by filing with a secretary of state or similar office may still qualify as reporting companies, according to both firms. Greenberg Traurig says such entities may need to report beneficial ownership information about their foreign owners. Several entity types are exempt, including some public companies, banks, securities brokers and dealers, insurance companies, and registered investment companies and advisers, so each foreign entity should check the criteria. Foreign companies generally do not need to report US persons, and are exempt from reporting US persons who are company applicants.

Deadlines

BDO says foreign reporting companies must file within 30 calendar days after receiving notice that their US registration is effective, and that transition rules applied to foreign entities registered before the interim final rule was published. Neither article gives penalty amounts, so we do not state any. Foreign individuals must still report changes to information submitted for their FinCEN IDs, according to Greenberg Traurig.

What it means for founders

Consider a hypothetical case. Priya is an Indian founder with a company formed in India that plans to register in a US state to sell there. That structure is a foreign entity registering to do business, so it is the type the sources say may still report. A founder who instead forms a new company under US state law would be a domestic company under the rule as the firms describe it. The structure, not the founder’s passport, drives the answer, so confirm your facts with a US adviser. Tamara News does not give legal advice.

Practical next steps

List where each entity was formed and where it is registered. Check the exemption list against your business. Note the 30-day clock from the date a US registration becomes effective. Keep records of ownership in case banks, partners or states ask for them, since reporting relief at the federal level does not remove other transparency rules, such as the UK identity verification deadline at Companies House or the beneficial ownership rules we described in our Vietnam company formation guide. If you are weighing jurisdictions for a new company, see our company formation service, and use FinCEN’s own page at fincen.gov/boi for official updates.

Beneficial ownership questions

Is beneficial ownership reporting over for US companies?

Yes. According to BDO and Greenberg Traurig, FinCEN’s final rule permanently exempts US companies and US persons.

When was the final rule issued?

FinCEN issued it on 11 August 2026 and it became effective on 14 August 2026, according to Greenberg Traurig.

Do foreign companies still report?

Foreign entities registered to do business in a US state may still qualify as reporting companies, according to both firms.

What is the filing deadline?

BDO says foreign reporting companies file within 30 calendar days after notice that their US registration is effective.

Do foreign companies report US owners?

BDO says foreign companies generally do not need to report beneficial owners who are US persons.

Where do I check for updates?

FinCEN publishes updates on its beneficial ownership information page. Take advice from a US lawyer for your own structure.

Sources

IBM’s ‘Legacy’ Mainframe Business Just Delivered a Surprise

IBM reported its IBM Q3 2026 earnings on October 21, beating profit expectations and raising its full-year revenue outlook. The company said it now expects 4% to 5% revenue growth for 2026. That outlook is carried by strength in its software division and renewed demand for its IBM Z mainframe line. The results, filed with the SEC the same day, mark one of the stronger quarters in IBM’s multi-year turnaround effort.

Enterprise server rack wiring tied to the IBM Q3 2026 earnings mainframe story

What drove the IBM Q3 2026 earnings beat

Two businesses did most of the work. Software revenue grew on continued enterprise adoption of IBM’s AI and automation tools. At the same time, the IBM Z mainframe franchise saw renewed order activity. That is a notable result for a product line many analysts had written off as a legacy business in slow decline. Coverage of the results described the mainframe performance as a surprise, given Wall Street’s expectations heading into the quarter.

IBM’s raised full-year guidance signals something specific: management expects both trends to hold through the rest of 2026, not just produce a one-quarter spike. A 4% to 5% revenue growth rate would be among IBM’s strongest full-year results in years. That marks a real shift. IBM’s top line barely grew for much of the past decade before this turnaround effort began.

Analysts covering the stock pointed to the mainframe order strength as the more surprising half of the beat. Software growth had already been trending upward for several quarters. A pickup in mainframe demand, though, was not something most forecasts had priced in heading into the earnings call.

AI spending reaches IBM’s traditional businesses

The quarter illustrates a broader pattern in enterprise technology spending. AI investment is no longer confined to chipmakers and cloud providers. IBM’s software gains came largely from clients layering automation and AI tooling onto existing systems. That includes the same mainframe environments that process the bulk of global banking and insurance transactions. This gives IBM a different kind of AI exposure than companies that sell GPUs or cloud capacity directly. IBM is monetizing AI adoption inside infrastructure enterprises already depend on, rather than selling the underlying hardware itself.

Whether that pattern continues depends on two things. First, enterprise IT budgets need to hold up through the rest of the year. Second, competitors need to stay unable to offer comparable automation tools at lower cost. IBM is betting that deep integration with mainframe and legacy systems is hard to replicate quickly. That is also why a mainframe order uptick matters more for IBM’s outlook than it would for a company without that same installed base of enterprise customers.

Enterprise buyers themselves have described the appeal in similar terms during recent industry surveys. Moving AI workloads onto systems they already run, rather than standing up new infrastructure, cuts both cost and integration risk at once. IBM’s quarter suggests that argument is translating into actual contract signings, not just survey responses. That distinction matters for anyone trying to gauge whether the trend has staying power.

What happens through the rest of 2026

IBM’s next real test comes with its full-year results early next year. That is when the 4% to 5% revenue growth guidance either holds or gets revised. Investors will also watch two other things. Does software momentum broaden beyond the segments that drove this quarter? And does mainframe order strength reflect a genuine multi-year refresh cycle among large customers? Or is it a shorter-term bump tied to a handful of specific deals?

If the mainframe strength proves durable, it would mark a turning point. IBM has spent years defending that product category against predictions of terminal decline. If it fades by the next earnings cycle, though, this quarter will likely be remembered differently: a one-off boosted by AI-era enthusiasm, rather than a lasting shift in enterprise buying patterns. Either way, the next two quarterly reports should settle the question one way or the other. Until then, IBM’s own guidance remains the clearest signal of how confident management is in what this quarter showed. The company has staked much of its multi-year turnaround narrative on exactly this combination of steady software growth and a revived mainframe franchise, so a repeat performance next quarter would carry real weight with investors who have watched IBM promise a comeback before.

More enterprise tech coverage

This earnings season is proving eventful across the technology sector. See our coverage of TSMC’s Q3 2026 earnings and AI chip demand, Microsoft’s Maia 300 chip plans, and Anthropic’s Q3 2026 revenue results.

IBM earnings: frequently asked questions

  • Did IBM beat earnings expectations in Q3 2026? Yes. IBM’s third-quarter results beat profit expectations and came with raised full-year revenue guidance.
  • What is IBM’s new 2026 revenue guidance? IBM now expects 4% to 5% revenue growth for 2026, an increase from its prior outlook.
  • What drove IBM’s strong quarter? Software revenue growth and renewed demand for the IBM Z mainframe line were the two main contributors.
  • Is IBM’s mainframe business growing again? Yes. Mainframe order activity picked up in the quarter, a result commentators described as a surprise given the product line’s legacy reputation.
  • How is IBM benefiting from AI spending? IBM is monetizing AI adoption through automation tools sold into existing enterprise software and mainframe environments, rather than through chip or cloud sales.
  • When will IBM’s next results confirm the trend? IBM’s full-year 2026 results, expected early next year, will show whether the revised guidance held.

Sources and further reading

Tesla Beat Delivery Estimates — So Why Did Profit Drop 43%?

Tesla released its Tesla Q3 2026 earnings on October 21, after market close. Revenue came in at $28.05 billion, flat compared with $28.1 billion a year earlier and in line with the roughly $28.06 billion analysts expected. Deliveries reached 486,532 vehicles, down 2.1% year over year but well above the 461,974 consensus estimate.

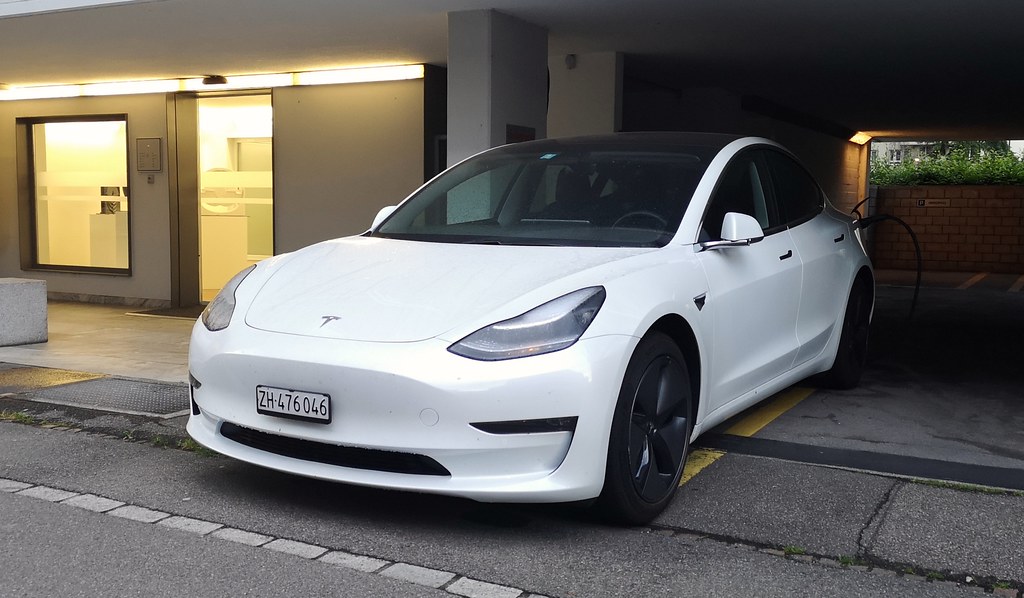
A Tesla Model 3, part of the lineup covered in the Tesla Q3 2026 earnings report

The headline numbers behind the Tesla Q3 2026 earnings

Production totaled 464,391 vehicles. That means Tesla sold more cars than it built in the quarter, trimming inventory by 22,141 units. Days of supply fell to 11 from 15 in the second quarter. Energy storage deployments reached 13.7 gigawatt-hours. That was up from 12.5 GWh a year ago but short of the roughly 15.9 GWh analysts had forecast.

Full self-driving subscriptions climbed 67% to 1.74 million active users. That figure includes upfront purchases, as defined in CEO Elon Musk’s 2025 pay package. Tesla’s robotaxi fleet passed nearly 2 million cumulative unsupervised miles by quarter-end. That milestone came about a month after the Cybercab model joined the Austin fleet.

Where the profit numbers tell a different story

Non-GAAP earnings per share hit $0.48. That beat the $0.45 consensus but was down 4% from $0.50 a year earlier. GAAP net income fell 43% to $787 million, or $0.22 per share. Operating income dropped 56% to $718 million. That pushed the operating margin down to 2.6% from 5.8% a year ago.

Operating expenses rose 39% to $4.78 billion. Research and development spending jumped 69% to $2.76 billion. Stock-based compensation totaled $1.17 billion on top of that. Regulatory credit revenue, which has cushioned Tesla’s margins in past quarters, fell 73% to $113 million from $417 million a year earlier.

Total gross margin did improve. It rose to 19.6% from 18.0% a year ago and 16.8% in the second quarter. Automotive gross margin excluding credits reached 18.1%, up from 15.4% a year earlier. Tesla said “battery availability continued to be the limiting factor in increasing auto volumes in the quarter.” That points to a supply constraint rather than weak demand.

Wall Street’s initial reaction was mixed. Several analysts noted that the delivery beat masked a weaker profit picture, while others pointed to the improving gross margin trend as evidence the battery bottleneck is easing gradually rather than worsening. The split in reactions reflects a broader debate among Tesla watchers about whether volume growth or margin recovery should be weighted more heavily when judging the company’s quarter. Bulls point to the delivery beat and improving margin trend as signs the worst of the battery constraint is over. Bears counter with a simpler fact: a 43% drop in net income is hard to wave away.

Energy and services move in opposite directions

Energy revenue fell 16% to $2.88 billion. Tesla partly attributed that drop to tariff-related customer refunds. Services and other revenue told a brighter story. It rose 33% to $4.61 billion, with a record $734 million in gross profit. That suggests Tesla’s repair, charging and software businesses are scaling faster than vehicle sales.

Spending, cash and what comes next

Capital expenditure reached $4.73 billion in the quarter. That was down from $5.79 billion in the second quarter but up sharply from $2.25 billion a year earlier. Nine-month capex now totals $13.01 billion. Free cash flow came in at $1.53 billion, a reversal from negative $1.09 billion in the second quarter. It still remained well below the $3.99 billion generated a year ago. Tesla ended the quarter with $45.4 billion in cash and investments.

Management had previously guided to more than $25 billion in 2026 capex. It did not update that figure in the Q3 letter. Hitting it would require roughly $12 billion in fourth-quarter spending alone, a sharp jump from recent quarterly totals. Tesla also said it ended the quarter with “the largest backlog for our passenger vehicles in four years.” That detail points to demand outpacing what battery supply currently allows the company to build. How quickly Tesla can resolve that bottleneck, rather than any single quarter’s delivery number, is likely to be the key variable determining whether margins recover meaningfully in 2027. Investors will get their next read on that question soon. Tesla reports fourth-quarter results early next year. That report will also show the final tally against management’s full-year capex target.

More EV and auto industry coverage

For more on this earnings season, read our reports on Boeing’s Q3 2026 delivery recovery, Goldman Sachs and Wells Fargo’s Q3 results, and the IMF’s 2026 global growth forecast.

Tesla earnings: frequently asked questions

  • Did Tesla beat earnings estimates? Tesla’s non-GAAP EPS of $0.48 beat the $0.45 consensus, and deliveries of 486,532 topped the 461,974 estimate.
  • Why did Tesla’s profit fall despite beating estimates? GAAP net income dropped 43% because operating expenses rose 39%, led by a 69% jump in R&D spending, and regulatory credit revenue fell 73%.
  • What limited Tesla’s vehicle production? Tesla said battery availability was the limiting factor on auto volumes during the quarter.
  • How many FSD subscribers does Tesla have? Active FSD subscriptions reached 1.74 million, up 67% year over year, including upfront purchases.
  • Did Tesla update its 2026 capex guidance? No. Tesla’s prior guidance of more than $25 billion for 2026 was not revised in the Q3 letter.
  • How much cash does Tesla have? Tesla ended Q3 2026 with $45.4 billion in cash and investments.

Reporting sources

Boeing’s Delivery Numbers Just Sent a Quiet Signal to Airlines Everywhere

Boeing is finally stringing together the kind of production numbers it needs to convince investors its recovery is real. The planemaker’s Boeing Q3 2026 deliveries report, released on October 13, showed another steady quarter of commercial aircraft handovers, continuing a rebound that began after years of production caps, safety reviews and supply-chain bottlenecks following the 737 MAX crisis and the 2024 door-plug incident.

Boeing’s own investor release and trade coverage from Centre for Aviation put September deliveries at 57 commercial aircraft against 165 new orders for the month, part of a broader third-quarter total the company detailed in its October 13 statement. The figures matter beyond Boeing’s own balance sheet: the company’s delivery pace has become a proxy for how much new aircraft capacity airlines worldwide can actually count on through the rest of the decade.

What’s behind the Boeing Q3 2026 deliveries recovery

Boeing has spent much of the past two years working through a regulator-imposed cap on 737 MAX production rates, a cap the Federal Aviation Administration put in place after the January 2024 door-plug blowout exposed quality-control failures at Boeing’s Renton factory and at supplier Spirit AeroSystems. Lifting and gradually raising that cap has been the single biggest driver of Boeing’s delivery recovery through 2026, alongside efforts to stabilize its supplier base after Spirit AeroSystems’ integration back into Boeing.

The steadier cadence shown in the Q3 figures suggests those fixes are holding under real production pressure rather than just clearing a backlog. Boeing’s full third-quarter financial results, due October 27, will show whether the delivery pace is translating into the cash flow and margin improvement investors have been waiting for since the MAX grounding years.

Why airlines are watching the numbers so closely

Airlines around the world have had to delay fleet renewal and route expansion plans repeatedly because Boeing — and, to a lesser extent, Airbus — simply couldn’t deliver aircraft on the schedules originally promised. Carriers that ordered 737 MAX jets years ago have absorbed years-long delays, forcing some to keep older, less fuel-efficient aircraft flying longer than planned or lease replacement capacity at a premium.

Boeing Q3 2026 deliveries

A sustained, predictable delivery pace from Boeing would let airlines plan capacity additions with more confidence heading into 2027 scheduling, particularly on routes where MAX variants are the primary aircraft ordered. It would also ease some of the fleet-age pressure that has kept maintenance costs elevated industry-wide while newer jets sat unbuilt.

What happens next for Boeing

Boeing’s full Q3 earnings report on October 27 will add detail the delivery announcement alone doesn’t provide — cash burn, defense-unit performance and progress on the 777X program, which has faced its own repeated delays separate from the 737 MAX issues. Analysts will also be watching whether the September delivery pace holds into the fourth quarter or whether supplier constraints resurface, as they have multiple times since the production cap was first imposed.

Tamara News has also covered other corners of this quarter’s earnings season in its reporting on Goldman Sachs and Wells Fargo’s Q3 results and the start of bank earnings season.

Frequently asked questions about Boeing Q3 2026 deliveries

How many aircraft did Boeing deliver in the third quarter of 2026?

Boeing’s September figures alone showed 57 commercial aircraft delivered against 165 new orders, part of a broader third-quarter total detailed in the company’s October 13 investor release.

Why did Boeing’s deliveries fall so far behind in the first place?

A production cap imposed by the FAA after the January 2024 door-plug incident, combined with supply-chain problems at supplier Spirit AeroSystems, limited how many 737 MAX jets Boeing could build and hand over for roughly two years.

Has the FAA’s production cap been lifted?

Boeing has been working through a gradual increase in permitted production rates rather than a single full lift, with the steadier Q3 delivery cadence suggesting those increases are holding under real output pressure.

When does Boeing report full Q3 financial results?

Boeing’s full third-quarter earnings report is scheduled for October 27, 2026, which will include financial detail beyond the delivery and order numbers already released.

How does this affect airlines?

A steadier delivery pace lets airlines plan fleet renewal and route expansion with more confidence, after years of delays that forced many carriers to keep older aircraft in service longer than planned.

Is the 777X program affected by these numbers?

The delivery figures released so far cover primarily the 737 MAX program; the 777X has faced its own separate, repeated delays that the full Q3 earnings report is expected to address.

Sources

Oil Markets Are About to Flip — Here’s Why 2027 Looks Nothing Like 2026

The US government’s own energy forecasters are now predicting a sharp reversal in the oil market within about a year. The latest oil price forecast 2027 from the Energy Information Administration calls for a tightening market through the rest of 2026, followed by a supply glut that pushes prices sharply lower in 2027 — a two-act forecast that has traders and producers planning for very different conditions just months apart.

The EIA’s Short-Term Energy Outlook, summarized by Yahoo Finance and other outlets this month, projects Brent crude averaging around $105 a barrel in the fourth quarter of 2026 before dropping to roughly $84 in 2027 as new supply — much of it from outside the OPEC+ alliance — comes online faster than demand grows.

Why the oil price forecast 2027 flips so sharply

The near-term tightness, according to the EIA’s analysis, stems largely from disruption risk tied to the Strait of Hormuz, the chokepoint through which roughly a fifth of global oil supply normally passes. Attacks and airspace warnings around Gulf shipping routes earlier this year pushed insurers and traders to price in a larger risk premium than usual, even though the agency expects flows through the strait to normalize by the end of 2026 if current conditions hold.

Once that risk premium fades and new non-OPEC+ production — largely from the United States, Brazil and Guyana — continues ramping up as scheduled, the agency expects supply to outrun demand growth through 2027, which is what drives its forecast for a meaningful price drop. The EIA has revised its 2026-2027 forecasts by more than 13% in recent months as these competing forces have shifted the outlook.

What OPEC+ can and can’t do about it

OPEC+ members have already signaled they expect the market to come close to balance through 2026 even as they maintain elevated output levels agreed earlier this year. The bloc’s own monthly reports have acknowledged the same supply growth from producers outside the group that the EIA is counting on to create next year’s glut, leaving OPEC+ with limited room to defend prices through further voluntary cuts without ceding more market share to rivals.

oil price forecast 2027

That dynamic — a cartel reluctant to cut further while outside supply keeps growing — is part of why the EIA’s 2027 number assumes prices fall regardless of what OPEC+ decides at its next scheduled meetings. Energy analysts tracking the forecast say the bigger wildcard is whether Gulf shipping disruptions flare up again, which would delay the glut rather than prevent it.

What happens next for oil markets

The EIA updates its Short-Term Energy Outlook monthly, so the next revision will show whether the agency is holding to its current view or adjusting again based on how shipping conditions in the Gulf and non-OPEC+ production actually develop through the winter. Businesses that budget around fuel costs — airlines, shipping firms and manufacturers — are watching the 2027 glut forecast closely, since a price drop of that scale would meaningfully ease input costs if it materializes as projected.

For related coverage of the forces shaping markets this quarter, see Tamara News’s reporting on the Federal Reserve’s upcoming October rate decision and on the start of Wall Street’s bank earnings season.

Frequently asked questions about the oil price forecast 2027

What is the EIA’s 2027 oil price forecast?

The agency expects Brent crude to average around $105 a barrel in the fourth quarter of 2026 before falling to roughly $84 in 2027, as new supply outpaces demand growth.

Why does the EIA expect prices to tighten before they fall?

Near-term tightness is tied to a risk premium from disruption around the Strait of Hormuz, which the agency expects to fade as shipping conditions normalize later this year.

What’s driving the expected 2027 supply glut?

Continued production growth from non-OPEC+ producers, particularly the United States, Brazil and Guyana, is expected to outrun demand growth once near-term shipping risks ease.

Can OPEC+ prevent the price drop?

Its options are limited. Further voluntary output cuts would cede more market share to non-member producers, and the group’s own reports already anticipate the same outside supply growth driving the EIA’s 2027 forecast.

How often does the EIA update this forecast?

The Short-Term Energy Outlook is revised monthly, so the next release will show whether actual shipping and production conditions are tracking the current projection.

Who benefits most from lower oil prices in 2027?

Airlines, shipping companies and manufacturers that rely heavily on fuel as an input cost stand to benefit most if the forecast drop materializes as projected.

Sources